Welcome! Where would you like to log in?

Sign up and get
PRO free for 14 days
Once your PRO trial is over you can continue using Landlord Studio GO completely free.
By continuing you agree to our Terms & Conditions.

Visiting from the
United Kingdom?
Please visit our United Kingdom site for a better experience
Continue
Real Estate Accounting: The Definitive Guide For 2026
Whether you own one unit or a hundred having a solid understanding of real estate accounting is essential for success in the industry

Read summarized version with:


Real estate accounting is a specialized field that requires an understanding of the unique financial aspects of the real estate industry. It encompasses everything from tracking revenue and expenses to ensuring compliance with tax laws and regulations.
Whether you're an accidental landlord managing one or two properties, or a property manager managing hundreds of units, having a solid understanding of real estate accounting is essential for success in the industry. In this article, we explore some of the most important aspects of real estate accounting, including the different types of accounting used in real estate, IRS real estate expense categories, the importance of bookkeeping, the role of a real estate accountant, and more.
What is Real Estate Accounting?
Real estate accounting involves performing monthly and yearly financial tasks to ensure smooth operations and strong cash flow. It deals with potential property revenue and taxes. As with any accounting practice, tracking income and expenses is crucial for creating a clear overview of each property's cash flow, which can help you scale your real estate business, prepare for audits, and accurately file taxes.
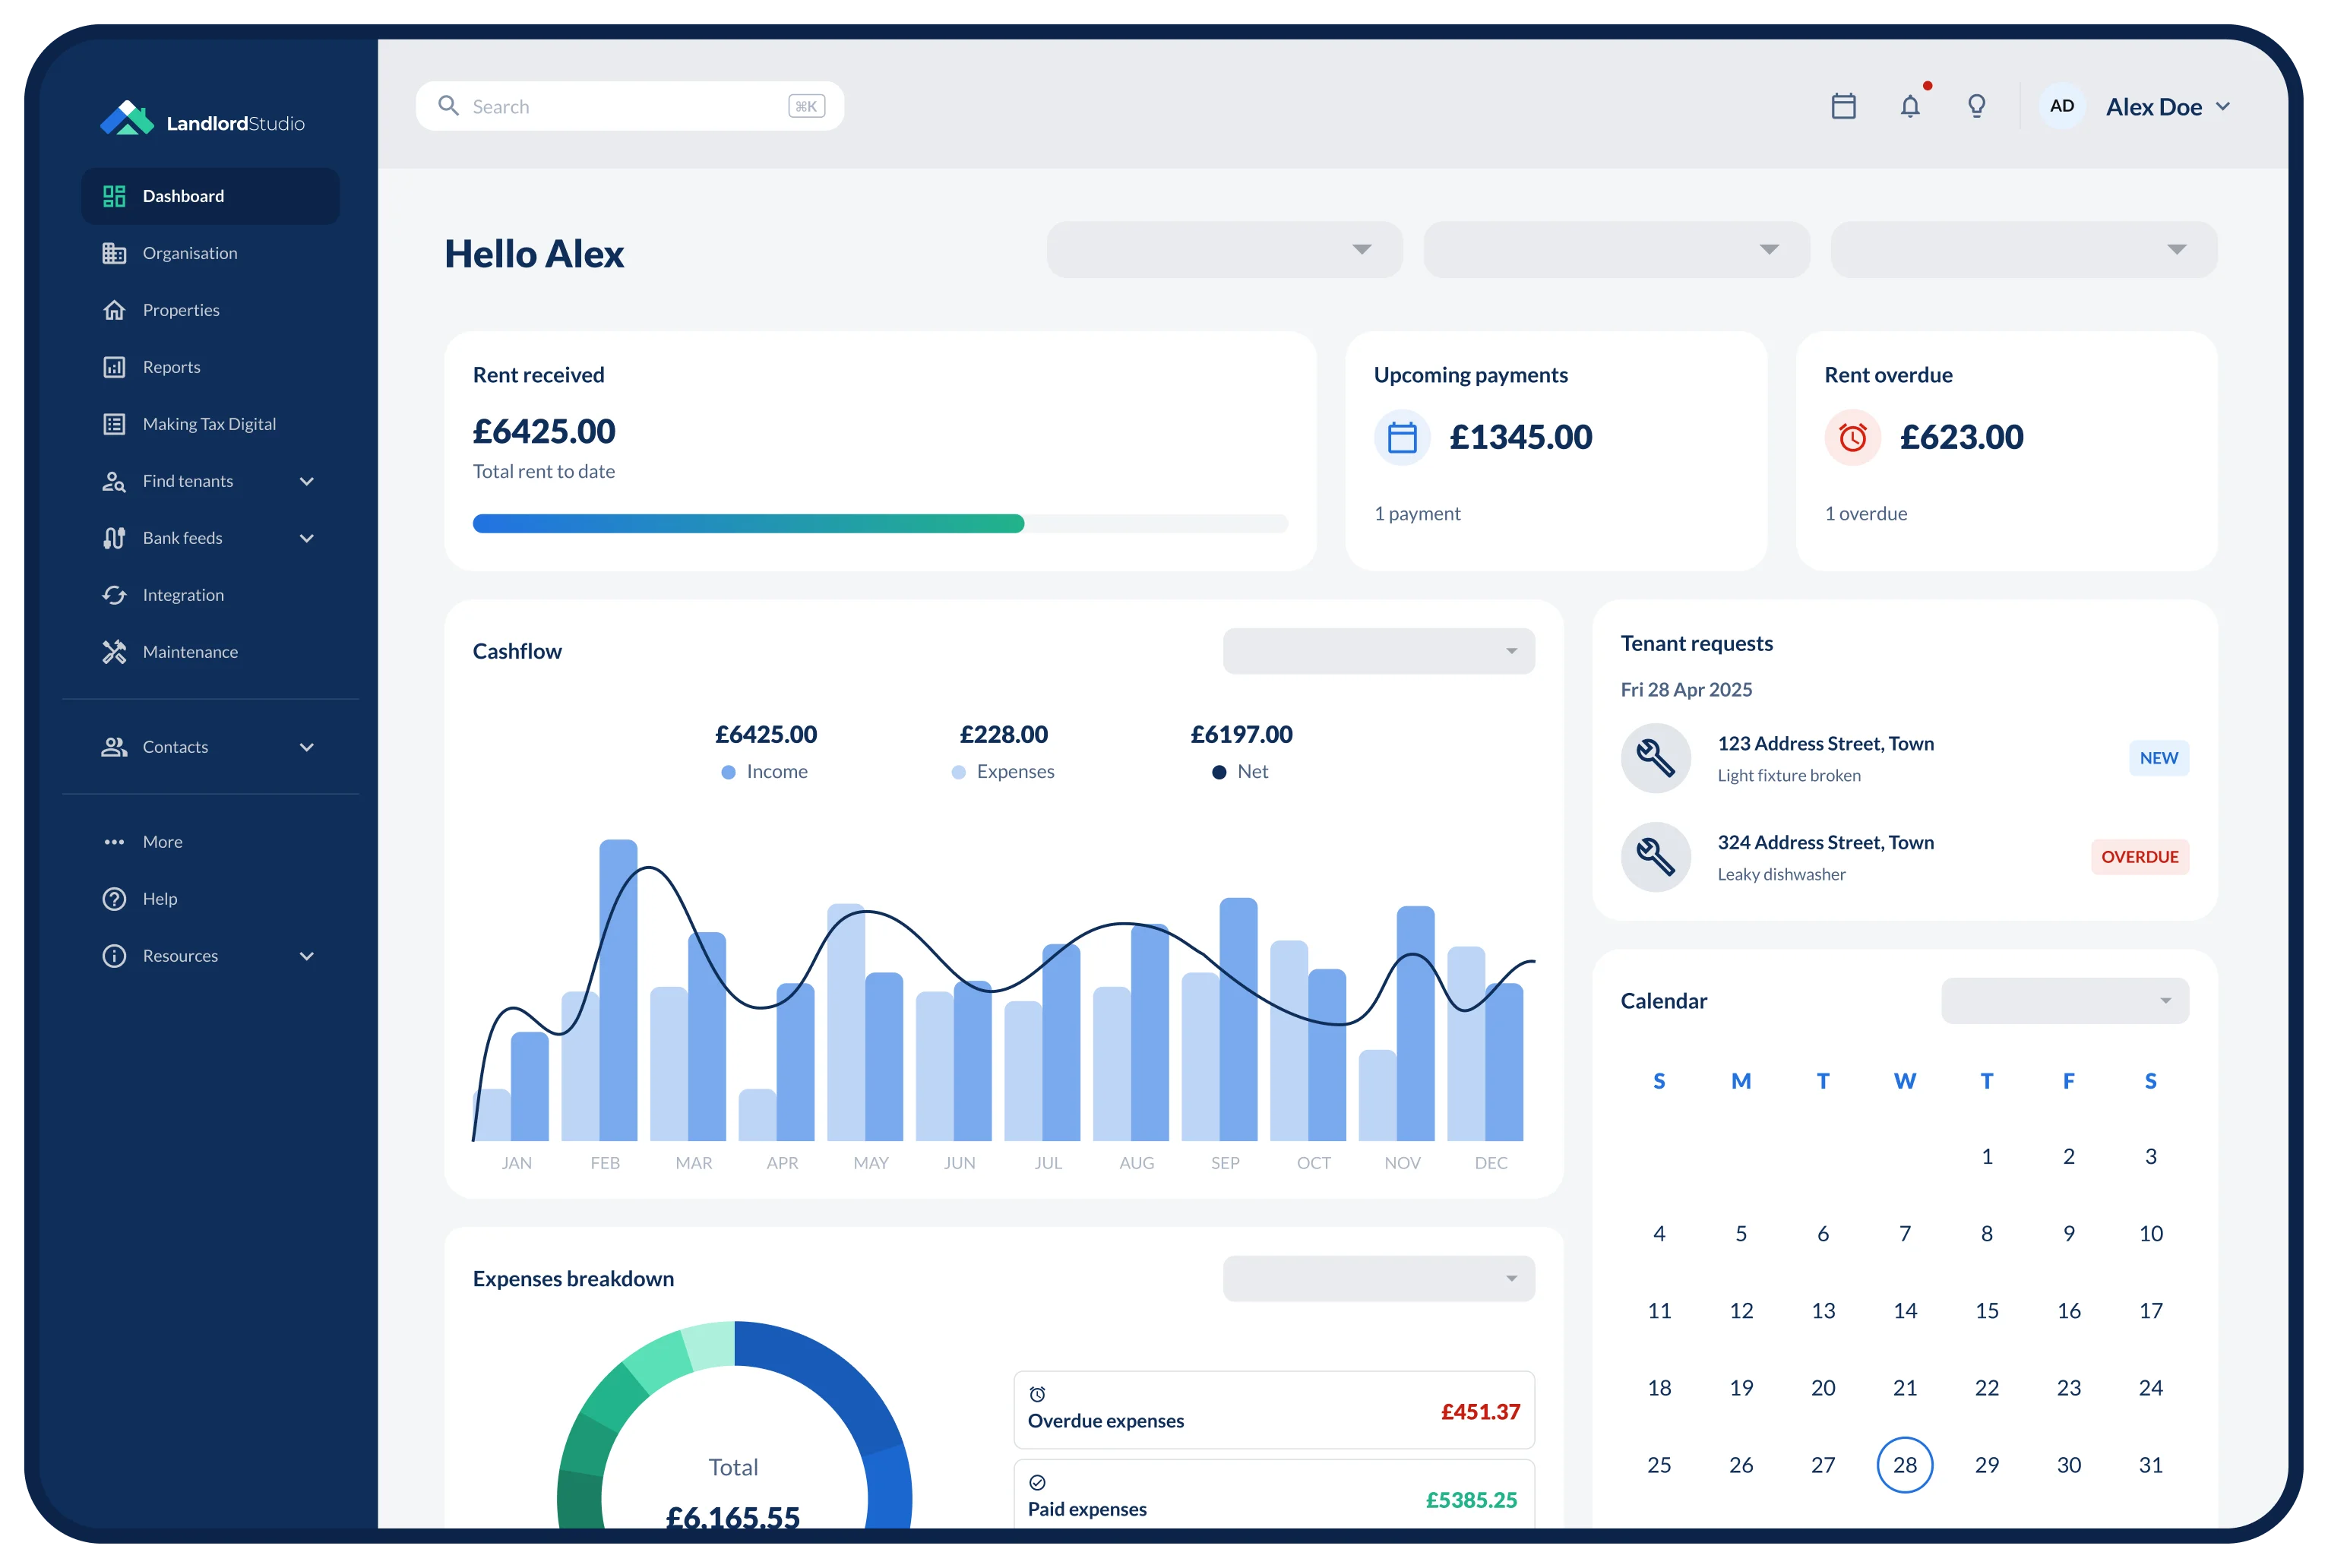
Landlord Top Tip: To get ahead, consider investing time in purpose-built real estate accounting software like Landlord Studio. Landlord Studio makes real estate accounting easy with features like a rent collection and automated income tracking, a built-in receipt scanner, bank feeds and fast reconciliation, and powerful customizable financial reporting. Learn more here →
Real Estate Accounting Basics – What to Track?
Although the scale of operations differs from person to person and portfolio to portfolio, the underlying accounting practices remain the same.
Regardless of whether you are just starting out or have gained considerable traction, the following list outlines the essential expense categories every real estate investor needs to track as stipulated on the IRS Schedule E form 1040.

Real Estate Tax Deductible Expense Categories
- Advertising: Any out-of-pocket expenses for the purpose of advertising your property are deductible business expenses.
- Auto and travel: Auto and travel expenses include vehicle mileage, airfare, and half of the meals you purchase while traveling.
- Cleaning and maintenance: You can deduct cleaning and any routine maintenance costs.
- Commissions: This includes commissions to someone to find you a tenant but not any commissions you pay to a real estate agent when buying a property.
- Insurance: Regardless of the type or number of policies you have, insurance premiums are deductible as a rental business operating expense.
- Legal and other professional fees: A few examples include asking a lawyer to oversee paperwork, such as new lease documents, fees for tax preparation, and CPA costs. If you use property management software like Landlord Studio, you can also deduct these fees.
- Management fees: Property management fees average between 8 - 12 percent of your monthly rental income and are generally deductible.
- Mortgage interest: Investment property owners can list their mortgage interest as a business expense.
- Other interest: You can also deduct interest from other loans, including interest on credit cards.
- Repairs: A repair is necessary to keep the property in good working order but doesn’t increase the property’s market value and is deductible.
- Supplies: An example of this could be notepads or, if you self-manage, you may purchase a toolkit for property maintenance.
- Taxes: You can record any property taxes you pay to your local government as a Schedule E deductible expense.
- Utilities: If you cover things like gas, electric, water, heating, AC, or internet for your tenants, you can deduct these as utility expenses.
- Depreciation expense or depletion: Properties (not the land itself) are considered assets with a value that reduces over the period of your ownership due to wear and tear. As such, residential rental properties can be depreciated over 27.5 years and the value deducted.
- Other (list): If you have any further expenses related to the ownership, maintenance, or management of your property, list them under the Other section. If you aren’t 100 percent sure something is deductible, seek advice from a qualified tax professional.
Why You Need Accurate Real Estate Accounting
Maintaining up-to-date accounts offers numerous benefits. The primary objective of real estate accounting is to provide a powerful tool that enables you to make financially sound decisions for the growth and profitability of your real estate business.
The secondary objectives of real estate accounting are to ensure you maximize your end-of-year deductions so you don’t end up overpaying your taxes while remaining audit-proof.
While it's not necessary to have complete knowledge of financial management, it requires a willingness to learn, make changes, and stay on top of essential accounting tasks throughout the tax year.
For an affordable solution to your accounting needs, you can download our rental accounting spreadsheet template or create a free Landlord Studio GO account. Landlord Studio GO is designed to simplify the accounting process for landlords with less than four units, offering an easy-to-use income and expense management system, essential reports, and a mobile app so you can update your accounts in near real time.
Learn more about Landlord Studio pricing →

Accounting Vs. Bookkeeping for Real Estate
The terms "bookkeeping" and "accounting" are often used interchangeably, but when it comes to maintaining a real estate business, they refer to distinct activities. Generally, bookkeeping activities include tasks such as:
- Tracking income and expenses.
- Monitoring debit and credit card charges.
- Establishing a system for rent collection, receipts and invoices.
- Reconciling payments to verify transactions against bank statements for accuracy.
- Ensuring sound payroll procedures (if applicable).
Accounting, on the other hand, encompasses a broader range of financial tasks and responsibilities. Consider the following when contemplating accounting as a whole:
- Conducting financial analyses or audits to gain insights into your portfolio’s financial health.
- Ensuring compliance with legal requirements and business regulations.
- Preparing for tax time as required.
- Understanding profit, loss, and gains accurately.
- Generating quarterly and annual financial statements and reports.
- Budgeting and forecasting.
Understanding the distinction between bookkeeping and accounting instills confidence and enables you to delegate responsibilities to other professionals in these critical areas.
Real Estate Accounting Best Practices
Now that you understand the significance of maintaining proper real estate accounting and have a good grasp of what financial information you need to track, it's essential to explore bookkeeping best practices. In the real estate sector, these five components can differentiate financially responsible investors from those who depend on unorganized or obsolete records in their accounting processes.
1. Monthly Review
Performing a monthly review of your accounts, whether through an automated accounting system or with a financial manager, is crucial to catch any errors and make necessary adjustments promptly.
2. Accurate Reporting Procedures
Accurate reporting requires accurate financial data, which can be easily achieved through monthly reviews. Generating reports such as profit and loss statements, income statements, and tax documents becomes effortless with automated software.
3. Separate Personal and Business Funds
Creating a separate business account for your real estate transactions helps you keep track of your income and expenses accurately. It also allows for easy connection to your real estate accounting software and eliminates the need for manual work.
4. Itemize All Transactions
Proper itemization of your financial accounts saves time and effort during tax season. Familiarize yourself with Schedule E deductions and other relevant categories to manage your expenses and income streams efficiently.
5. Learn Local Requirements
Real estate regulations and requirements vary based on location, so it's essential to familiarize yourself with local policies and regulations to comply with state tax obligations or business license requirements. Understanding these details can change how you manage or outsource your bookkeeping needs.
Common Real Estate Accounting Mistakes
If you're new to accounting in any industry, it's normal to make mistakes as you get accustomed to managing financial records and creating a bookkeeping system that fits your personal style and needs. Here are some common real estate accounting mistakes to avoid:
- Forgetting to back up your files, data, and other records: If you use a cloud-based system, make sure the automatic backup function is enabled. If you maintain files in other ways, such as on paper or spreadsheets, create a system to duplicate these files. The worst accounting nightmare is having to find critical information and not being able to.
- Inaccurate expense categorization: If you're trying to itemize expenses for maximum tax benefits, don't assume that each category is the same. If you're not a tax expert, hire one to assist you in determining which expenses should be filed together and which should be filed separately.
- Lack of communication with invested parties: Real estate income can come from various sources, and you may rely on several people to finalize a transaction or manage investments. With accounting, never assume that these individuals know what you need in terms of documentation. Clearly express your needs and provide timely reminders for new documents, tax statements, or other proof of purchase.
How to Simplify Your Real Estate Accounting Needs
Simplifying your bookkeeping process is key to staying organized and minimizing stress, especially during tax season. There are two effective strategies for doing this:
- Use automation and bank rules wherever possible. Connecting your bank account to a bookkeeping platform like Landlord Studio allows you to automate transaction tracking and reconciliation. With features like bank feed auto-matching and customizable bank rules for recurring expenses, you can save hours of manual data entry each month while reducing the risk of costly errors.
- Stay consistent with your bookkeeping. Don’t leave everything until the end of the year. Instead, block off time once a month—or even once a week—to update your books. Doing this regularly ensures you maintain accurate records, helps you avoid forgetting key details about certain transactions, and makes year-end tax preparation far easier.
- Outsourcing to a consultant or accountant: As your real estate business grows, it may be worth investing in a financial manager who can handle your accounts. A professional can save you a significant amount of time, effort, and money. You can invite your accountant to easily collaborate in Landlord Studio.
Staying current with your bookkeeping has another major benefit: it helps you identify tax-deductible expenses in real-time, like travel, mileage, and depreciation. These deductions may seem minor individually, but they can add up to substantial savings. When tax time rolls around, you can simply run a report on your categorized expenses to get instant insights, ensuring no deductions are overlooked.
Streamline Your Real Estate Accounting With Landlord Studio
A suitable real estate accounting system for your portfolio should take into account the unique aspects of your real estate business. You can find a flexible solution that caters to your specific needs, whether it's managing properties, dealing with tenants, or tracking commissions.
Landlord Studio pairs real estate accounting software that can simplify your accounting work with a range of powerful property management tools. Its features include:
- Invoicing and receipts,
- Reminders for late payments,
- Connect your bank accounts for easy transaction reconciliation,
- In-built receipt scanner,
- Automated mileage tracker,
- Online rent collection,
- Property maintenance tracker,
- Rental listings,
- Tenant screening,
- And more…


Final Words: Real Estate Accounting
We hope this guide to real estate accounting has provided you with a comprehensive understanding of the fundamental principles, best practices, and common mistakes to avoid in real estate accounting.
Remember, the first step of nailing your real estate accounting is getting the basics right. Make sure you have separate bank accounts set up for business and personal use. Update your records on a monthly or even weekly basis. Communicate effectively with all parties involved. Digitize your receipts, reconcile transactions, and run reports and analyze your data regularly.
The easiest way to stay on top of these tasks is to use the latest technology and software to streamline your processes. By doing so, you can ensure the financial success of your real estate business and make informed decisions that lead to long-term growth and profitability.
Create your free Landlord Studio account today to streamline your real estate accounting and maximize your portfolio profitability.
You Might Also Like
- The Best Alternative to Spreadsheets for Rental Property
- How To Categorize Rental Property Expenses
- What Is a Rent Roll and Why Is It Important For Real Estate?
- 9 Best Real Estate Accounting Software 2025
Real Estate Accounting FAQs
What is real estate accounting?
Real estate accounting is a type of accounting that focuses on financial practices related to real estate transactions. It involves tracking revenue generated by various properties and complying with tax requirements.
How is accounting used in real estate?
Accounting in real estate is used for a variety of reasons. One of the main purposes is to provide an accurate and clear picture of the overall financial health of a business. Additionally, accounting is used for tax purposes and to quickly assemble required documents for an audit if necessary.
What is the difference between bookkeeping and accounting in real estate?
Bookkeeping in real estate primarily focuses on keeping accurate records of invoices, expenses, and payroll. Accounting in real estate involves analyzing financial data and making strategic decisions based on that data. While the two terms are often used interchangeably, bookkeeping refers to a narrower subset of financial activities within a business.
Is real estate accounting difficult?
Real estate accounting can be challenging, but with time and effort invested into learning the fundamentals of accounting practices and organization, it can be easily mastered.
What are the duties of a real estate accountant?
A real estate accountant is responsible for managing the financial aspects of buying, selling, leasing, and renting properties. Also known as property accountants, they play an important role in preparing documents for tax season and ensuring compliance with financial regulations.
Do I need a real estate CPA?
It depends on the complexity of your real estate transactions and financial situation. If you have multiple properties, partnerships, or investments, a real estate CPA can help you navigate the tax implications and optimize your financial strategy. However, if your real estate activities are straightforward, you may be able to handle your accounting needs without a CPA.
How to find a real estate CPA?
One way to find a real estate CPA is to ask for referrals from other real estate professionals in your network, such as real estate agents, brokers, or investors. You can also search online directories, such as the National Association of Real Estate Companies (NAREC) or the American Institute of CPAs (AICPA), for certified public accountants with expertise in real estate accounting.
Can I use a spreadsheet for real estate accounting?
Yes, you can use a spreadsheet for real estate accounting, but it may not be the most efficient or accurate method, especially if you have multiple properties or transactions. A dedicated real estate accounting software can offer features such as automated data entry, transaction tracking, and tax preparation that can save you time and minimize errors. However, if you have a small real estate business and are comfortable with spreadsheet software, it may be a viable option.


About Landlord Studio

Landlord Studio is an easy to use property management and accounting software designed for landlords.
Find and screen tenants, collect rent online, track income and expenses, run reports, and more - all for free.
Create your FREE account with Landlord Studio today.

From finding tenants to filing taxes. Reduce vacancies and maximize your portfolio ROI with software designed for you.
Get started for free