



Mortgage Calculator
Work out your monthly mortgage payment on a home or rental property - principal, interest, taxes, insurance and PMI - and check whether the rent covers the debt.
How to manually calculate your monthly mortgage payment
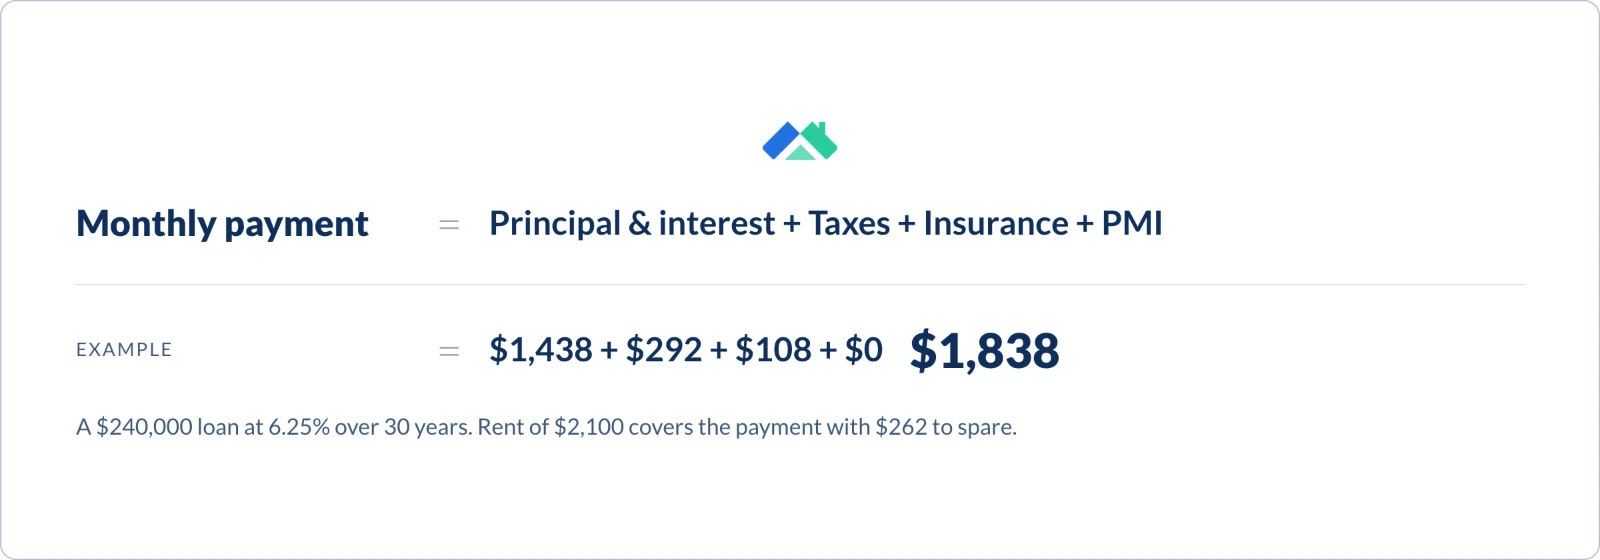
Your payment is principal and interest, plus property tax, insurance and PMI. Lenders call it PITI, and it's what actually leaves your account each month.
Work out principal and interest
This is fixed for the life of a fixed-rate loan and depends on the loan amount, rate and term.
Add taxes and insurance
Both are usually escrowed monthly and both rise over time, unlike your principal and interest.
Add PMI if you're under 20% down
It falls away once you reach 20% equity, so it's temporary rather than permanent.
Worked example
A $300,000 loan at 6.5% over 30 years, with $350 a month in property tax and $135 in insurance.
Monthly payment = $1,896 + $350 + $135 + $0 = $2,381
Other calculators you might be interested in

Rental Yield Calculator
Gross and net yield, cash flow and cash-on-cash return on a rental property.

Net Operating Income Calculator
Calculate net operating income before financing, the figure DSCR is built on.

BRRRR Investment Calculator
Model a full Buy, Rehab, Rent, Refinance, Repeat deal from purchase to refinance.

Manage up to 3 rental properties for free!
Sign up and get PRO free for 14 days. When the trial ends, keep tracking rent, expenses and reports for up to 3 properties, free forever with Landlord Studio GO.
By continuing you agree to our Terms & Conditions. · Already have an account? Log in
Financing a rental property
Mortgage Calculator
Principal and interest is only part of what leaves your account each month. Property taxes, insurance, HOA dues and any mortgage insurance are usually escrowed alongside it - together they make up PITI.
Budget on PITI, not on P&I alone.
Rentals are underwritten differently
Investment property loans usually need 20-25% down and carry rates roughly half a point above a primary residence. Lenders also check DSCR - whether the rent covers the debt by 1.20 to 1.25 times.
Why should you use our mortgage calculator?
- Shows the full PITI payment, not just principal and interest
- Adds property taxes, insurance, HOA dues and PMI
- Runs the DSCR test lenders use on investment properties
- Tells you the total interest you'll pay over the life of the loan
- Free, fast and no sign-up
FAQs
How is a monthly mortgage payment calculated?

Your monthly principal and interest payment is set by three things: the loan amount, the interest rate, and the term. A longer term lowers the monthly payment but increases total interest paid substantially.
Remember that principal and interest is only part of the cost. Property taxes, insurance, HOA dues and mortgage insurance are usually escrowed alongside it, which is why the full payment is often called PITI.
How much down payment do I need on a rental property?
Most conventional lenders want at least 20-25% down on an investment property, compared with as little as 3-5% on a primary residence. Rates are typically higher too, often by 0.5 to 0.875 percentage points.
The larger deposit and higher rate both exist because lenders treat rentals as higher risk - borrowers default on investment properties more readily than on the home they live in.
When do I have to pay PMI?
Private mortgage insurance protects the lender, not you, and is normally required when your down payment is under 20% on a conventional loan. It typically runs 0.5-1.5% of the loan amount a year.
Because investment property loans usually require 20-25% down anyway, PMI is less common on rentals than on primary residences.
What DSCR do lenders require on an investment property?
Debt Service Coverage Ratio is the property's net operating income divided by its annual mortgage payments. Investor lenders use it to check the rent covers the debt.
Most want at least 1.20 to 1.25 - meaning the NOI is 20-25% more than the mortgage. Below 1.0 the property does not cover its own loan, and financing becomes difficult on the terms you have modelled.