Welcome! Where would you like to log in?

Sign up and get
PRO free for 14 days
Once your PRO trial is over you can continue using Landlord Studio GO completely free.
By continuing you agree to our Terms & Conditions.

Visiting from the
United Kingdom?
Please visit our United Kingdom site for a better experience
Continue
Tax Implications of Converting Primary Residence To Rental Property
The tax implications of converting your primary residence into a rental: rental income, deductions, depreciation and capital gains tax.

Read summarized version with:


Converting a primary residence to a rental property can be a strategic financial move for many homeowners. With the rising demand for rental properties and the long-term wealth-building opportunities that real estate provides, it’s no surprise that more individuals are considering this transition.
Generally, speaking this means
However, before leaping in, it’s essential to understand the tax implications of converting your primary residence into a rental property and the potential benefits and pitfalls of becoming a landlord.
Why Consider Converting Your Primary Residence?
The decision to convert your primary residence into a rental property often stems from the desire for additional cash flow or long-term investment gains. Many homeowners find themselves in a position where they can benefit financially by holding onto their property rather than selling it.
Here are some key reasons why converting your primary residence to rental property might make sense:
- Increased Cash Flow: Renting out your home can provide a steady income stream, which can help offset mortgage payments, build equity, and contribute to other savings and investments.
- Tax Deductions: As a landlord, you may be eligible for various tax deductions related to your rental property, including expenses for repairs, maintenance, and management.
- Property Appreciation: Holding onto your property allows you to benefit from potential appreciation in value over time, which can lead to significant profits when you eventually sell.
- Low-Interest Mortgages: If your mortgage has a low interest rate, it may be financially advantageous to keep it while renting out the property.
Understanding the Tax Implications of Renting Your Primary Residence
This can all look very appealing on the surface. However, running a rental means running a business. There are overheads and expenses that need to be considered and ultimately, converting your primary residence to a rental property will affect your tax obligations. Thankfully, many of the expenses that come with operating a rental are in fact deductible, meaning, if you manage your rental property bookkeeping effectively you can mitigate your tax obligations significantly.
Here are some rental property tax considerations:
1. Reporting Rental Income
Once you begin renting out your home, you must report the income generated from rent on your tax return using Schedule E (Form 1040). The taxable income is calculated as the gross rental income minus allowable expenses and deductions.
2. Deductions for Rental Expenses
As a landlord, you can deduct various expenses related to managing and maintaining your rental property. Common rental property tax deductions include:
- Advertising Costs: Expenses incurred while marketing your property.
- Repairs and Maintenance: Costs for fixing issues or maintaining the property.
- Insurance Premiums: Including homeowner's insurance and landlord liability insurance.
- Property Management Fees: If you hire a management company.
- Mortgage Interest: Interest paid on your mortgage loan.
- Utilities: If you cover any utilities for the rental unit.
- Depreciation: A significant deduction that allows you to recover the cost of the property over time.
For example, if your converted rental property generates $24,000 in gross rental income and you have $18,000 in deductible expenses, your taxable net income would be $6,000.
3. Depreciation Benefits
One of the most significant advantages of converting a primary residence into a rental property is the ability to depreciate the property's value over time. The IRS allows landlords to depreciate residential rental properties over 27.5 years. This depreciation can significantly reduce your taxable income from the rental property.
Read more: How to Calculate Depreciation on a Rental Property [+Free Spreadsheet]
4. Passive Activity Losses (PAL)
Rental real estate activities are generally considered passive by the IRS. This means that if your expenses exceed your income (which can happen due to depreciation), you may incur passive activity losses (PAL). These losses can only be deducted against passive income and cannot offset other types of income (eg. W2 income) directly, they can be carried forward to future tax years.
5. Avoiding Self-Employment Tax
Income generated from rental properties is typically exempt from self-employment tax (FICA), which is applicable to earned income. This means that if you earn $50,000 from rental properties instead of self-employment activities, you won’t owe FICA taxes on that amount—providing additional financial relief.
Related: Everything You Need to Know About Rental Income Tax Rates
Potential Drawbacks of Converting Your Primary Residence
While there are numerous benefits associated with converting a primary residence into a rental property, there are also several potential pitfalls that new landlords should be aware of:
1. Capital Gains Tax Implications
One significant drawback is the potential capital gains tax owed when selling the converted rental property later on.
When selling a rental property:
- Profits from the sale are taxed at long-term capital gains rates (0%, 15%, or 20%, depending on your income bracket).
- Depreciation recapture tax applies on any claimed depreciation during ownership.
For instance, if you sold a converted rental property for $325,000 after claiming $40,000 in depreciation over five years. You would owe taxes on both depreciation recapture and any profit made from the sale after deducting closing costs.
Capital gains and depreciation recapture cannot be avoided, however, they can be deferred through tax strategies like a 1031 exchange. Understanding the nuance of strategies like these will help you build long-term wealth and is one of the reasons having a quality CPA on your side is so important.
2. Transition Challenges
Converting a primary residence into a rental requires careful planning and effort. A few things to consider before you make the transition include.
- Does your mortgage provider allow the change? Speak to your mortgage provider to make sure that changing the use of the property doesn’t breach your mortgage contract.
- Do you need a new insurance policy? Speak to your insurance provider and make sure you have an adequate landlord insurance policy for your property.
- Preparing the property: You must prepare the home for tenants by making necessary repairs and determining competitive market rent.
- Finding good tenants: What makes a good tenant? How do you set tenant criteria? How and where do you advertise your property? How should you manage the application process? And how are you supposed to screen tenants? All of these steps needed to be navigated efficiently and in compliance with federal and state landlord-tenant law.
- Understanding your legal obligations: Managing tenant relationships and ensuring compliance with local landlord-tenant laws can be daunting without prior experience. This includes getting legal documents like lease agreements drafted up, and even preparing for the worst by reading up on things like the eviction process.
- Collecting Rent: Once you’ve got a tenant you need to make sure you have a system in place to collect rent, preferably online, so you can avoid any cash flow issues that come with late and missed payments.
3. Financial Management
Ultimately, running a rental property means running a business. As such, you'll need to commit yourself to learning how to manage your rental property books so you can stay on top of your cash flow and operate a profitable rental business.
This means tracking all of your rental income sources, rent, late fees, tenant payable expenses, deposit deductions, etc. And tracking the various expenses related to maintaining your rental property. Records needed to be updated regularly with supporting documents (eg. receipts) filed away for future reference.
Create a budget that accounts for all potential costs—including maintenance, insurance changes, and taxes—to avoid financial surprises. You can use calculations like the 50% rule to make initial estimates.
The easiest way to manage your rental property income and expenses is to use purpose-built software like Landlord Studio.
Learn more about rental property accounting here →
Steps for Converting Your Primary Residence into a Rental Property
If you've decided that converting your primary residence into a rental property is right for you, follow these steps:
- Assess Financial Viability – Determine whether renting or selling is the better financial decision by evaluating potential rental income, ongoing expenses, and market conditions.
- Check HOA Rules – If your home is part of a homeowners association, confirm whether rentals are permitted and if any restrictions apply. Some HOAs have specific leasing requirements or rental caps.
- Review Your Mortgage Terms – If you have a mortgage, check with your lender to ensure that converting your home into a rental complies with your loan terms. Some mortgages, particularly owner-occupied loans, have restrictions on renting, and you may need to refinance into an investment loan.
- Update Insurance Policies – Notify your insurance provider that your property will be used as a rental and switch to a landlord insurance policy to ensure proper coverage.
- Obtain Necessary Permits – Research local rental regulations, as some municipalities require landlords to register their properties or obtain rental licenses before leasing.
- Prepare Your Home – Complete necessary repairs and improvements to attract quality tenants. Conduct a market analysis to determine a competitive rental price.
- Secure Quality Tenants – Screen tenants thoroughly with a background and credit check to reduce the risk of non-payment or property damage. Landlord Studio offers tenant screening services powered by TransUnion to provide you with detailed reports.
- Sign the Lease Agreement – Use a legally compliant lease agreement that outlines key terms, responsibilities, and rent payment expectations. Store digital copies in Landlord Studio for easy access and organization.
- Set Up Online Rent Collection – Make rent payments seamless by offering tenants an online rent payment option. Landlord Studio enables automated online rent collection with payment tracking and reminders.
- Implement Income and Expense Tracking – Keep track of rental income, mortgage payments, maintenance costs, and other expenses to stay organized. Landlord Studio’s built-in rental accounting features automate tracking and generate financial reports for tax time.
- Prepare for Rental Property Taxes – Rental properties come with unique tax considerations, including deductions for mortgage interest, depreciation, and repairs. Using Landlord Studio, you can generate year-end tax reports and export financial data to simplify tax filing.
How Can Landlord Studio Help You Convert Your Primary Residence Into A Rental Property?
Turning your home into a rental isn’t as simple as moving a tenant in. It requires planning and, if you want to operate a profitable rental, then it requires committed day-to-day management.
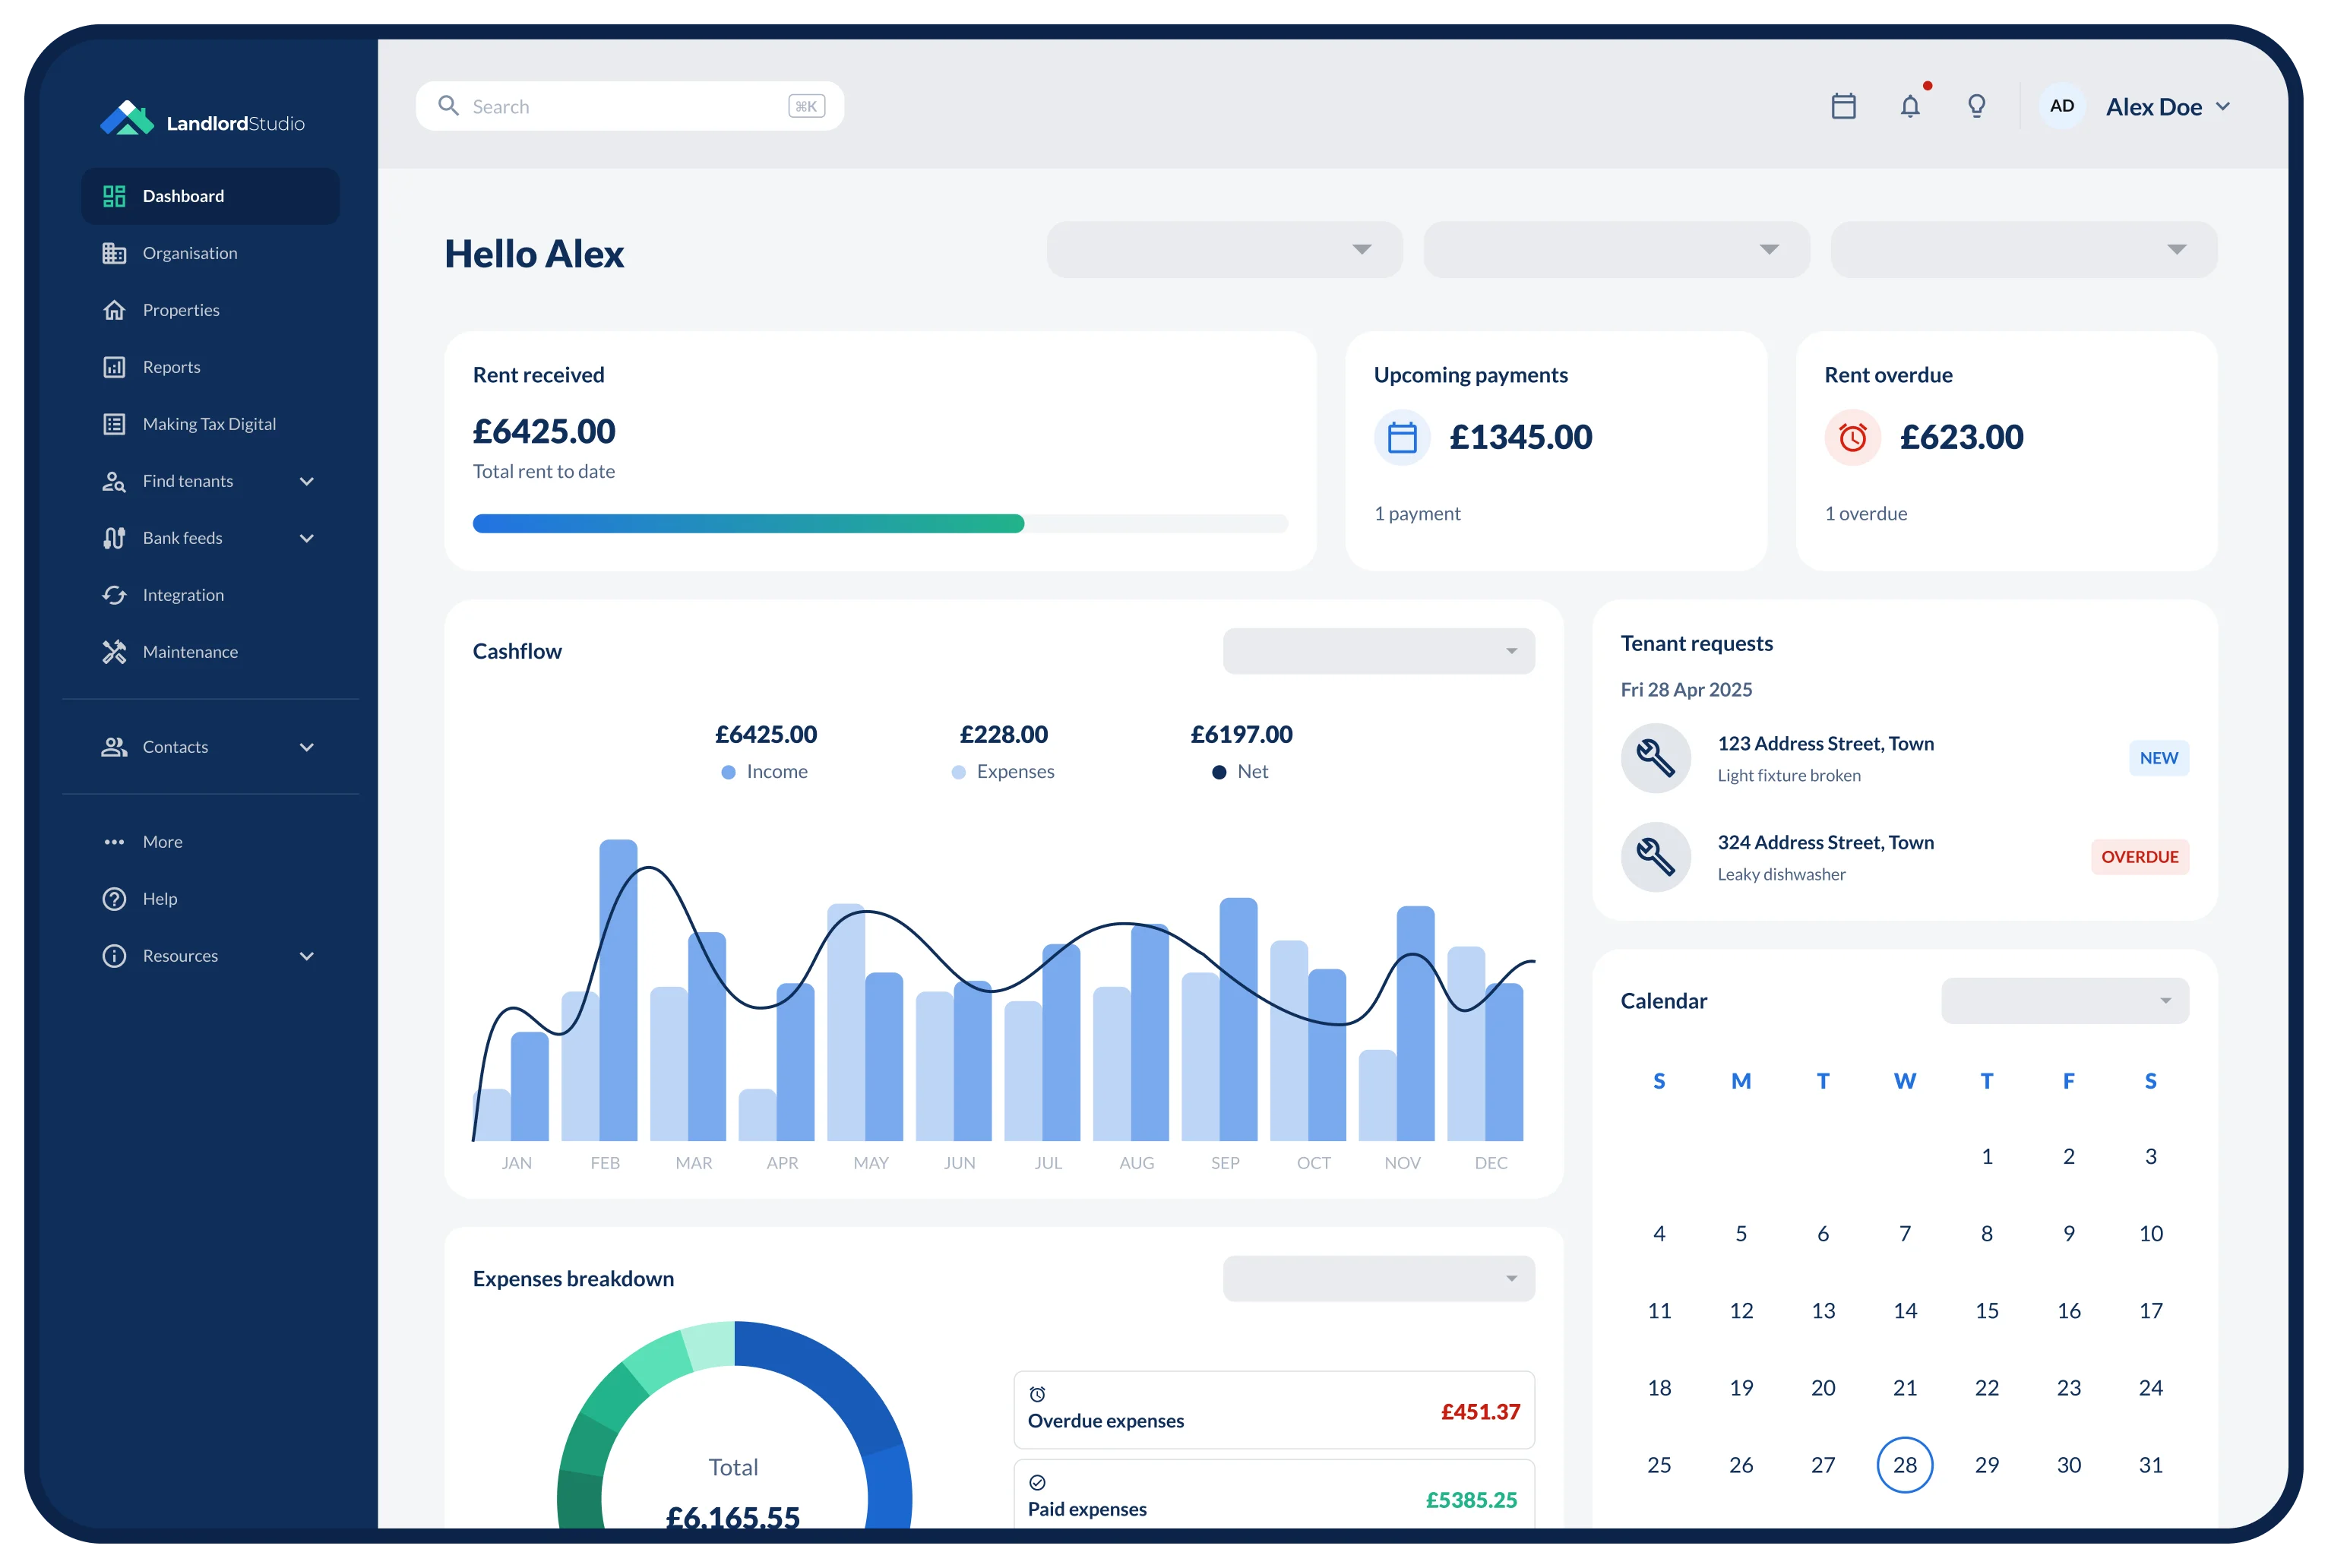
Landlord Studio can help you make the transition from homeowner to landlord with ease, streamlining every step of the process from managing and tracking property updates to finding great tenants to collecting rent to filing accurate tax returns and maximizing your rental property ROI.
- Financial Tracking – Estimate rental cash flow, track expenses, and generate reports to assess profitability.
- Tenant Screening – Run TransUnion-powered credit, criminal, and eviction checks to find reliable tenants.
- Lease & Document Storage – Store digital copies of leases, inspection reports, and important paperwork in one place.
- Online Rent Collection – Automate rent payments with built-in tracking, reminders, and reporting.
- Expense & Tax Management – Log income and expenses, categorize deductions, and generate tax-ready reports.
Tax Implications of Converting Primary Residence To Rental Property: Final Words
Converting your primary residence into a rental property presents both opportunities and challenges—especially concerning the tax implications of renting your primary residence. By understanding these factors and following best practices throughout the conversion process, homeowners can make informed decisions that enhance their financial well-being while navigating their new role as landlords effectively.
Before making any significant changes or decisions regarding taxes or real estate investments, consult with qualified professionals such as accountants or real estate attorneys who specialize in this area to ensure compliance with all local laws and regulations while maximizing potential benefits.
You Might Also Like
- 12 Things New Landlords Need To Know When Renting Out A House For The First Time
- Renting Out A Room In Your House: A Landlord's Guide
- 10 Things Investors Need To Know: How To Become A Landlord
- First-Time Landlord Checklist: 9 Things To Follow For Success
- The Landlord's Complete Guide To Rental Property Management
Frequently Asked Questions
What is the cost basis when converting my primary residence?
The cost basis typically includes the property's purchase price plus any capital improvements made during ownership and casualty losses claimed for tax purposes.
How long should I live in my home before converting it?
While there’s no strict rule regarding how long you must live in your primary residence before converting it into a rental property, many experts suggest at least one year for practical experience and stability.


About Landlord Studio

Landlord Studio is an easy to use property management and accounting software designed for landlords.
Find and screen tenants, collect rent online, track income and expenses, run reports, and more - all for free.
Create your FREE account with Landlord Studio today.

From finding tenants to filing taxes. Reduce vacancies and maximize your portfolio ROI with software designed for you.
Get started for free