



Read summarized version with:

ChatGPT

Gemini

Claude

Grok

Add as preferred on Google
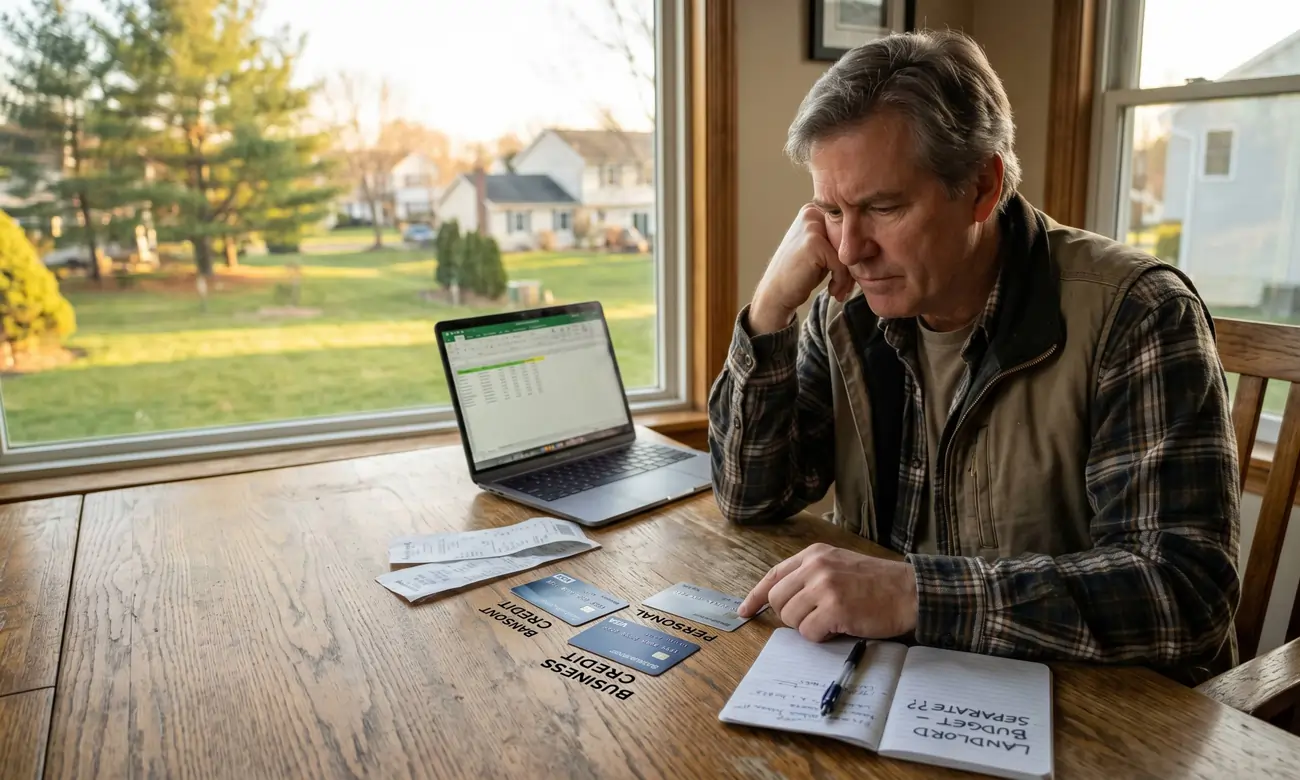
If you accidentally became a landlord, inherited a property, or started renting out a former home, there is a good chance your rental finances still run through the same bank account you use for groceries, holidays, and household bills.
You are not alone. With more than 71.6% of U.S. rental properties owned by private individuals rather than companies or LLCs, many DIY and first-time landlords begin this way because it feels easier in the beginning. When there is only one property and a handful of expenses, mixing everything together may not seem like a problem.
But even with one property, mixing personal and rental finances quickly becomes frustrating - particularly when tax time comes around, and you are left trying to remember what was personal and what was related to the property (as well as finding the expenses amongst your personal information).
It makes bookkeeping harder, tax time more stressful, and it becomes almost impossible to see whether your rental properties are actually making money.
Separating your rental business finances from your personal finances is one of the simplest ways to get more organised and more profitable.
The problem with mixing business with pleasure
The problem with mixing personal and business finances under one account is:
- More time spent categorising transactions
- A higher chance of missing deductible expenses
- Greater risk of errors at tax time
- Less visibility into how your rental business is performing
It can also create problems if you are audited.
The IRS expects landlords to keep accurate records of rental income and expenses. When everything is mixed together, proving what was business-related becomes much more difficult.
Why Separating Your Finances Makes Life Easier
Creating a dedicated bank account and credit card for your rental business gives you a much clearer picture of your finances.
1. Easier Bookkeeping
When every rental-related transaction runs through one account, your records are automatically cleaner.
Instead of sorting through hundreds of personal transactions, you can immediately see:
- Rent collected
- Mortgage payments
- Repairs
- Insurance
- Property taxes
- Contractor invoices
That makes monthly bookkeeping faster and easier.
2. Simpler Tax Filing
Tax preparation becomes much easier when all of your rental expenses are already separated.
You are less likely to:
- Miss deductible expenses
- Double-count transactions
- Forget important records
Instead, you can quickly generate reports and hand them to your accountant or use them to complete Schedule E.
3. Know Whether Your Property Is Actually Making Money
Many DIY landlords know how much rent comes in each month, but not how much they actually make after expenses.
Once your rental finances are separated, you can clearly see:
- Which properties are profitable
- Where expenses are increasing
- Whether your cash flow is improving or declining
This makes it much easier to make better investment decisions.
4. Stronger Legal and Liability Protection
If you own properties through an LLC, keeping your business finances separate is especially important.
Using the same account for personal and business spending can weaken the legal separation between you and the company.
In some situations, this can make it easier for someone to argue that the LLC is not truly operating as a separate business entity.
5. Easier To Scale
The more properties you own, the harder it becomes to manage everything manually.
Separating your finances early makes it much easier to:
- Add more properties
- Work with a bookkeeper or accountant
- Apply for financing
- Track performance across your portfolio
- Use digital tools and software
How To Separate Your Rental Finances From Your Personal Finances
The good news is that you do not need an accountant, a complicated business structure, or multiple properties to do this.
Even if you only have one rental property, you can usually get set up in an afternoon.
Step 1: Open a Separate Account Just for the Property
The easiest first step is to open a separate checking account used only for your rental property.
You do not necessarily need a formal business bank account if you own the property personally. Many landlords simply open a second checking account and use it only for rent and property expenses.
From that point forward:
- Deposit all rent payments into this account
- Pay all rental-related expenses from this account
- Do not use it for personal purchases
If you own properties through an LLC, open the account in the LLC's name.
Step 2: Get a Separate Credit Card
Using a dedicated business credit card makes it easier to track repairs, supplies, travel, and other expenses.
It also gives you a separate statement each month, which simplifies bookkeeping.
Step 3: Move Existing Automatic Payments
Update any recurring transactions so they come from the new account.
This might include:
- Mortgage payments
- Insurance
- Utility bills
- HOA fees
- Property management fees
- Software subscriptions
Step 4: Create a Clear Owner Draw Process
If you need to take money from your rental business for personal use, do not simply pay personal expenses from the business account.
Instead, transfer money to your personal account and record it as an owner draw or distribution.
That keeps your business records clean.
Step 5: Use Dedicated Landlord Software
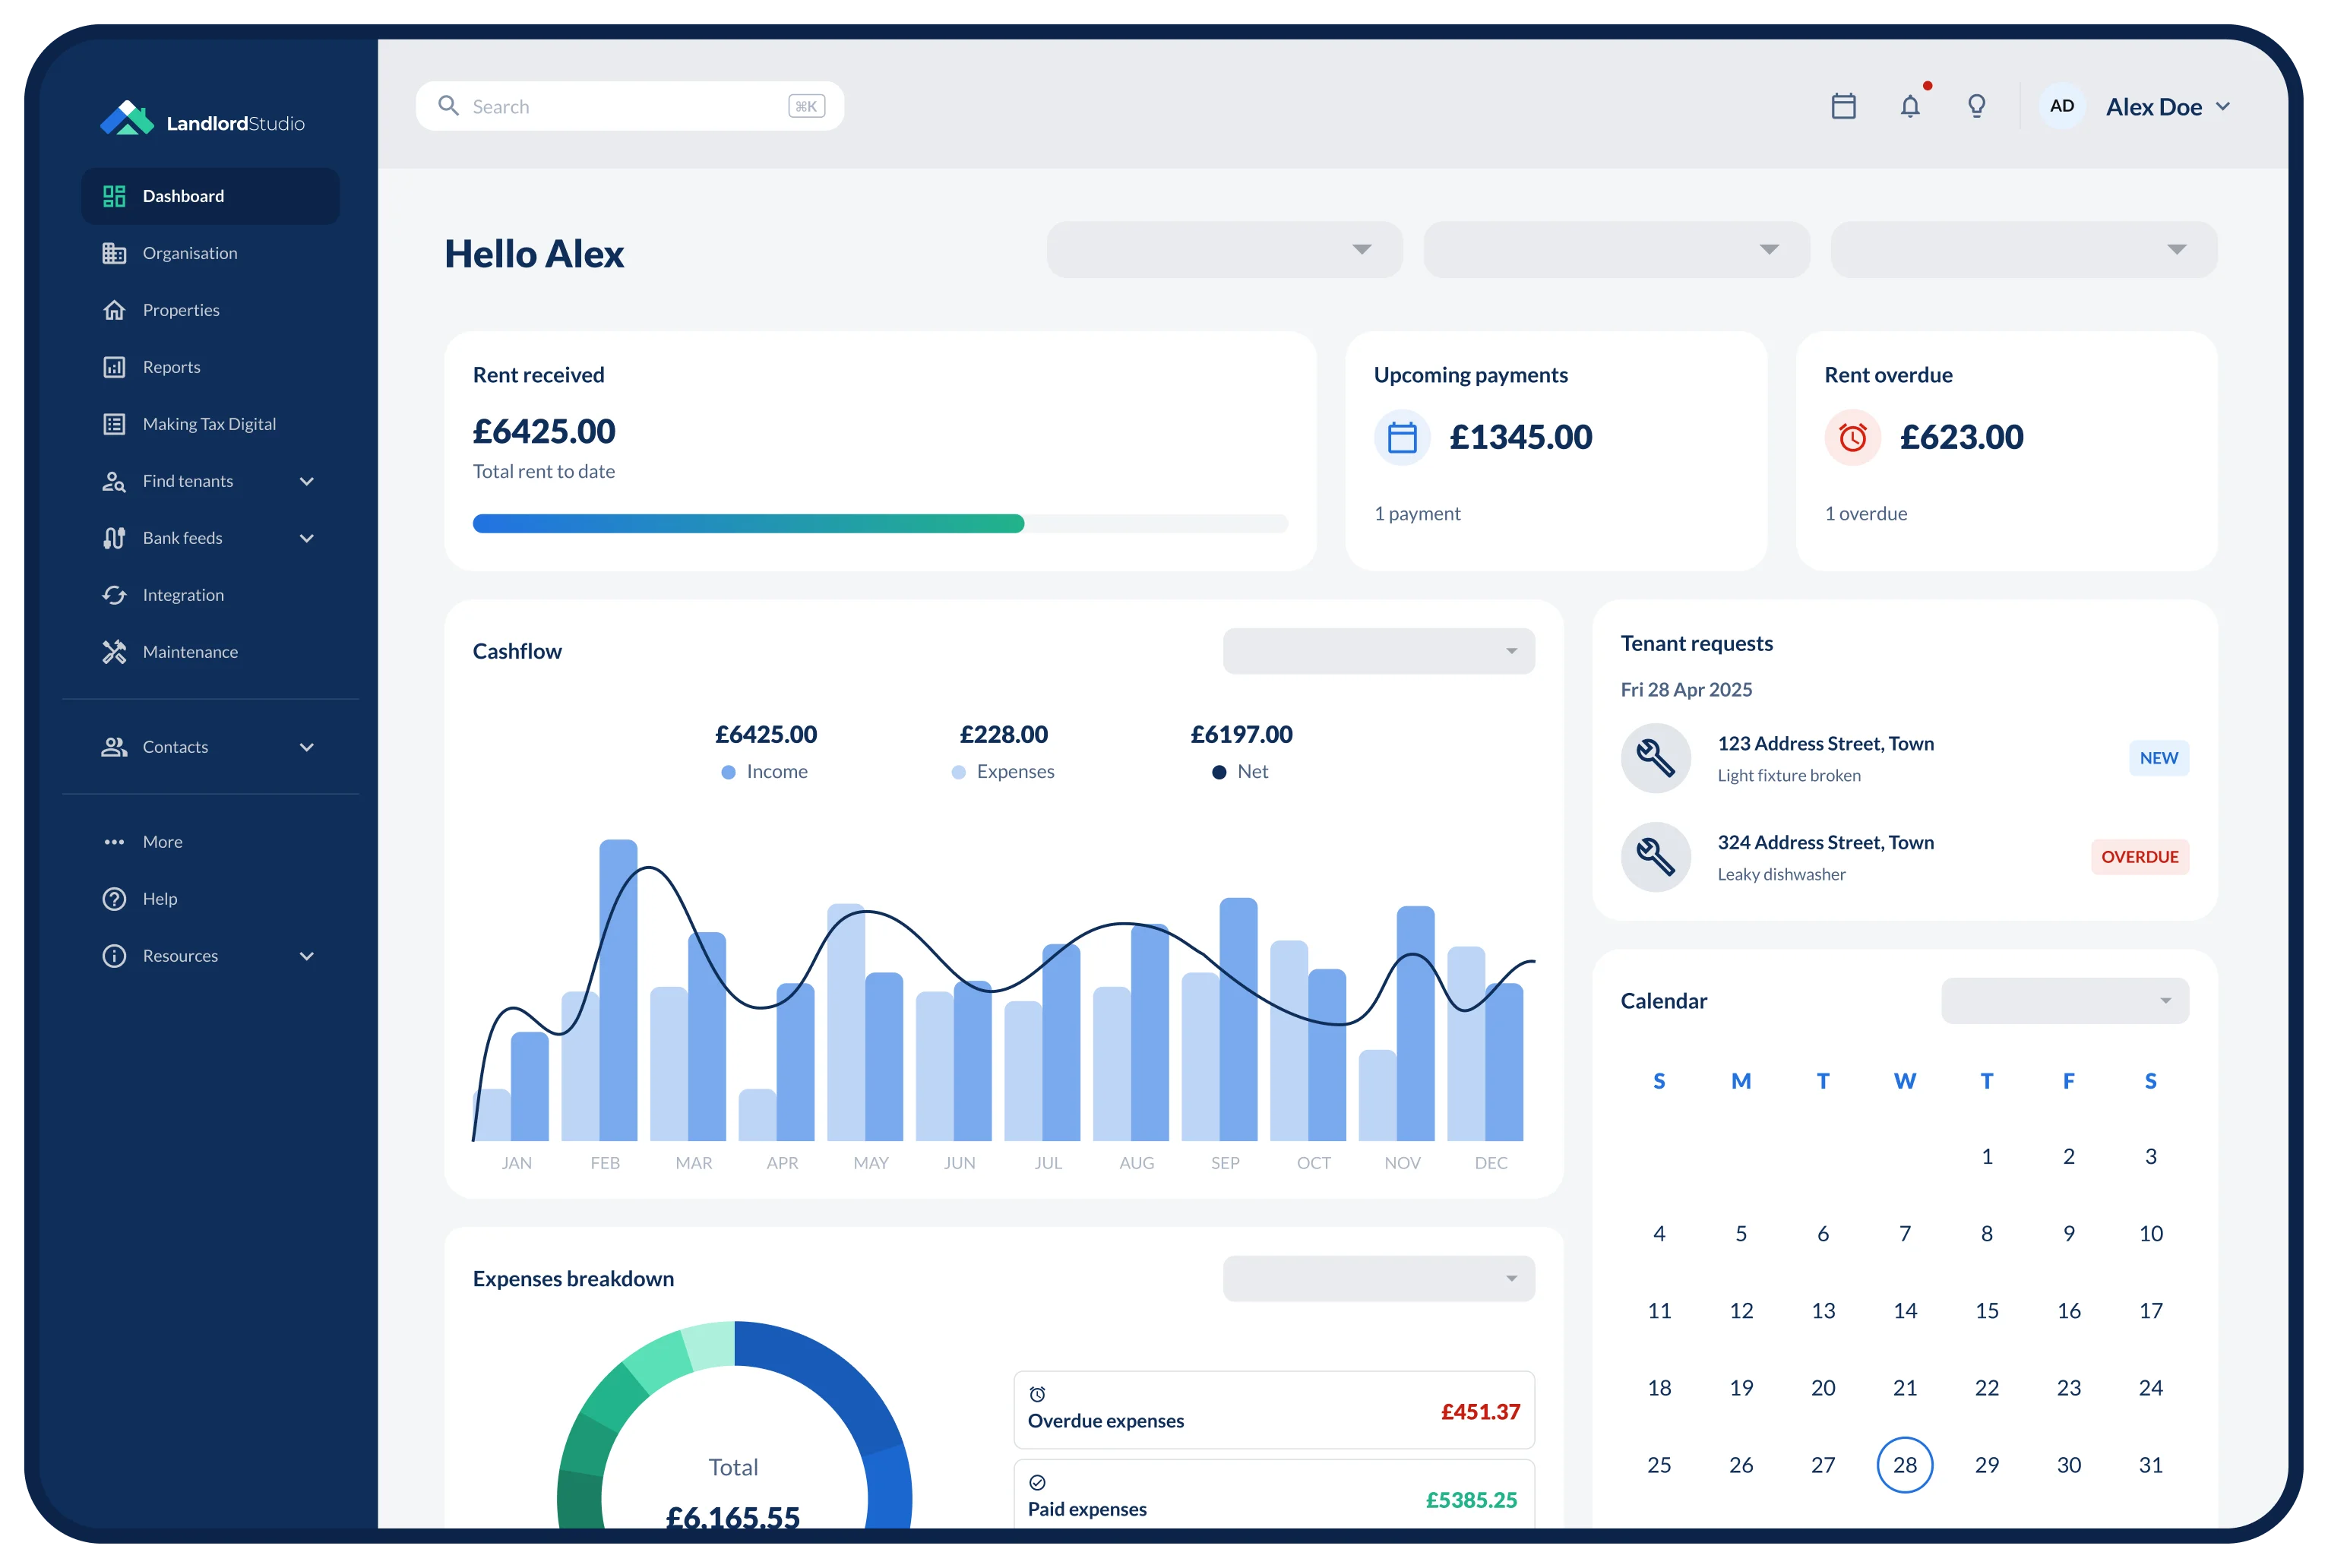
Once you have a separate account, connect it to rental property accounting software.
This allows you to automatically import and categorize transactions, making it easier to stay organised and generate reports.
Best DIY Landlord Bank Accounts
If you are just starting to get organised, you probably do not need anything complicated.
The best option is usually one that is easy to open, easy to use, and separate from your everyday spending.
Here are some of the most common choices landlords use in the US (please note that we are not sponsored or associated with any of these banks):
Chase Business Complete Banking
Good for landlords who want a traditional bank with local branches.
Pros:
- Large branch network
- Easy to open LLC accounts
- Integrates with most accounting software
Potential drawback:
- Monthly fees unless you maintain a minimum balance
Monzo
Monzo can be a good option for DIY landlords who want a simple, modern app and do not necessarily need a formal business account.
Many landlords use a separate Monzo account just for rental income and expenses.
Pros:
- Very easy to set up
- Strong app experience and instant spending notifications
- Pots feature is useful for setting aside money for repairs or taxes
Potential drawback:
- Better for landlords with one or two properties than larger portfolios
- Business features are more limited than those of traditional business banks
Wise
Wise is particularly useful for landlords who live abroad, own US property from overseas, or move money internationally.
Pros:
- Easy to hold and transfer multiple currencies
- Lower international transfer fees
- Good option for overseas or expat landlords
Potential drawback:
- Less useful if all of your banking is domestic
- Not designed specifically for property management
Bluevine Business Checking
Popular with small landlords and LLC owners.
Pros:
- No monthly fees
- High interest on balances
- Fully online
Potential drawback:
- No physical branches
Novo Business Checking
A common choice for landlords who prefer online banking.
Pros:
- No monthly fees
- Good app experience
- Easy integrations with bookkeeping tools
Potential drawback:
- Better for simple banking than complex cash management
Relay
Relay is popular with landlords and real estate investors because it allows you to create multiple sub-accounts.
For example, you can keep separate balances for:
- Security deposits
- Taxes
- Maintenance reserves
- Different properties
Pros:
- Multiple checking accounts under one login
- Good for portfolio landlords
- Easy expense organization
Potential drawback:
- Online-only
Mercury
Mercury is often used by landlords operating through an LLC or larger business structure.
Pros:
- Strong for business banking
- No monthly fees
- Good for landlords with multiple entities
Potential drawback:
- Designed more for businesses than specifically for landlords
Should You Use a Personal Account or a Business Account?
If you own one rental property in your personal name, you may be able to use a separate personal checking account dedicated only to your rental business.
However, once you:
- Own multiple properties
- Operate through an LLC
- Have a partner
- Want better bookkeeping and reporting
A dedicated business checking account is usually the better option.
Common Mistakes To Avoid
When landlords first separate their finances, they often make a few common mistakes:
- Continuing to occasionally use the business account for personal spending
- Forgetting to move recurring bills to the new account
- Using cash without keeping records
- Mixing multiple properties and personal spending in one account again
The key is consistency. Once you create a dedicated account, use it only for your rental business.
Start Small, Get Organised
Separating your business and personal finances is one of the easiest ways to become more organised as a landlord.
It makes bookkeeping easier, tax filing simpler, and gives you a much clearer view of how your rental business is performing.
Even if you only own one or two properties today, setting up a separate account now will save you time and stress as your portfolio grows.
The sooner you separate your finances, the easier everything else becomes.