Welcome! Where would you like to log in?

Sign up and get
PRO free for 14 days
Once your PRO trial is over you can continue using Landlord Studio GO completely free.
By continuing you agree to our Terms & Conditions.

Visiting from the
United Kingdom?
Please visit our United Kingdom site for a better experience
Continue
Cap Rate Formula: How to Calculate Cap Rate on a Rental Property
Cap rate is NOI divided by property value. Get the formula, worked rental examples, and what a good cap rate is for a US single-family rental.

Read summarized version with:


Cap rate is a rental property's annual net operating income divided by its value, expressed as a percentage. A single-family rental producing $10,800 of net operating income on a $200,000 value has a 5.4% cap rate ($10,800 ÷ $200,000 × 100). Cap rate deliberately ignores your mortgage, so it measures the property itself rather than your financing.
For US single-family rentals, cap rates averaged 7.3% in the fourth quarter of 2025, up from a low of 5.4% in late 2021, according to Arbor Realty Trust's Single-Family Rental Investment Trends Report Q1 2026. Single-family rental cap rates ran 160 basis points above multifamily cap rates in the same quarter, so judge a rental house against residential comparables rather than against institutional commercial deals.
Reviewed and updated August 2026. The benchmark ranges on this page are general national guides, not live local market data. Always compare a property against recent comparable sales in its own market.
The cap rate formula is the most widely used metric for evaluating rental property investments. Whether you're analyzing your first property or your tenth, understanding how to calculate cap rate accurately can make the difference between a profitable investment and a costly mistake.
Cap Rate Formula: Net Operating Income (NOI) ÷ Property Value × 100 = Cap Rate %
In this guide, you'll learn exactly how to calculate cap rate, what the formula means, how to interpret your results, and what constitutes a good cap rate for different property types and markets. We'll walk through real examples so you can apply this immediately to your investment analysis.
Cap Rate Formula
Cap Rate = (Net Operating Income ÷ Property Value) × 100
Where:
- Net Operating Income (NOI) = Annual rental income minus operating expenses
- Property Value = Current market value or purchase price
Example: A property generating $12,000 annual NOI worth $200,000 has a 6% cap rate ($12,000 ÷ $200,000 × 100 = 6%).
Calculate Your Property's Cap Rate
Use our free cap rate calculator to instantly calculate cap rate, cash flow, and return on investment for any property.
Calculate Cap Rate Now →Free • No signup required • Instant results
Cap Rate in Real Estate Key Takeaways
- Cap rate measures a rental property's potential return and is a common tool for evaluating real estate investments.
- It's especially useful for comparing properties and is widely used in commercial real estate.
- Cap Rate Formula: (Net operating income ÷ Purchase price) × 100.
- A cap rate between 4% and 12% is generally favorable, but context matters—consider future improvements and overall market conditions.
- Cap rate doesn't reflect changes in cash flow from upgrades or account for financing (leverage).
- While helpful, it should be used alongside other factors like location, property condition, and market trends.
- Cap rates vary by area and are influenced by rent, property values, and the local economy.
- This metric is most relevant to investors and lenders—not typical homebuyers.
- Cap rate compression happens when rising property prices lower returns, potentially limiting new investment opportunities.
What Is Capitalization Rate in Real Estate?
Capitalization rate, often referred to as the cap rate, is a metric used in real estate that indicates the rate of return that is expected from an investment property.
The cap rate is calculated by dividing the property's net operating income (NOI) by the asset value and is expressed as a percentage. This figure assists in gauging the potential return for real estate investors and can also be used to make predictions of the final capitalization rate, or terminal cap rate, when the property is sold.
While the cap rate provides a quick means of comparing similar real estate investments, it's essential to note that it shouldn't stand alone as the sole indicator of an investment's viability. It doesn't consider elements like leverage, the time value of money, or future cash flow from property enhancements, among other significant factors.
Understanding Cap Rate on Rental Property
The cap rate is one of the most popular metrics investors used to assess a rental property's profitability. Put simply, it represents the yield of a property over a one-year time horizon.
The capitalization rate reflects the property's inherent, unaltered rate of return, independent of leverage.

How to Calculate Cap Rate: Step-by-Step Process
Cap rate needs four numbers: gross rental income, operating expenses, net operating income and property value. Here is the whole calculation in one pass, using a $200,000 single-family rental renting for $1,500 a month.
- Gross rental income: $1,500 × 12 = $18,000 a year. Use market rent rather than the sitting tenant's rent, and add parking, storage, laundry or pet fees.
- Operating expenses: $7,200 a year. Include property taxes, landlord insurance, property management, maintenance and repairs, HOA fees, landlord-paid utilities, a vacancy allowance, and legal or accounting costs.
- What to leave out: mortgage payments, depreciation, capital improvements and income taxes. Cap rate is deliberately unlevered, so financing never enters the calculation.
- Net operating income (NOI): $18,000 - $7,200 = $10,800.
- Property value: $200,000. Use current market value for a property you already own, and the purchase price for one you are considering buying.
- Cap rate: ($10,800 ÷ $200,000) × 100 = 5.4%.
Run the numbers on your own property in the free cap rate calculator. It handles the income, expense and NOI arithmetic and returns the cap rate for you. Then come back to this page to work out whether that number is any good, using the residential benchmarks, the worked examples and the metric comparisons below.
Two things decide whether your cap rate is trustworthy: whether you used real expense figures rather than the seller's pro forma, and whether you compared the result against genuinely similar properties. Both are covered below.
Common Cap Rate Calculation Mistakes to Avoid
- Using pro forma numbers: Always verify the seller's claimed income and expenses with actual documentation
- Forgetting vacancy: No property is 100% occupied year-round
- Underestimating maintenance: Properties always need more repairs than expected
- Including mortgage payments: Cap rate measures property performance, not your financing terms
- Ignoring market comparisons: Your 8% cap rate might be great in one market but terrible in another
Ready to put this into practice?
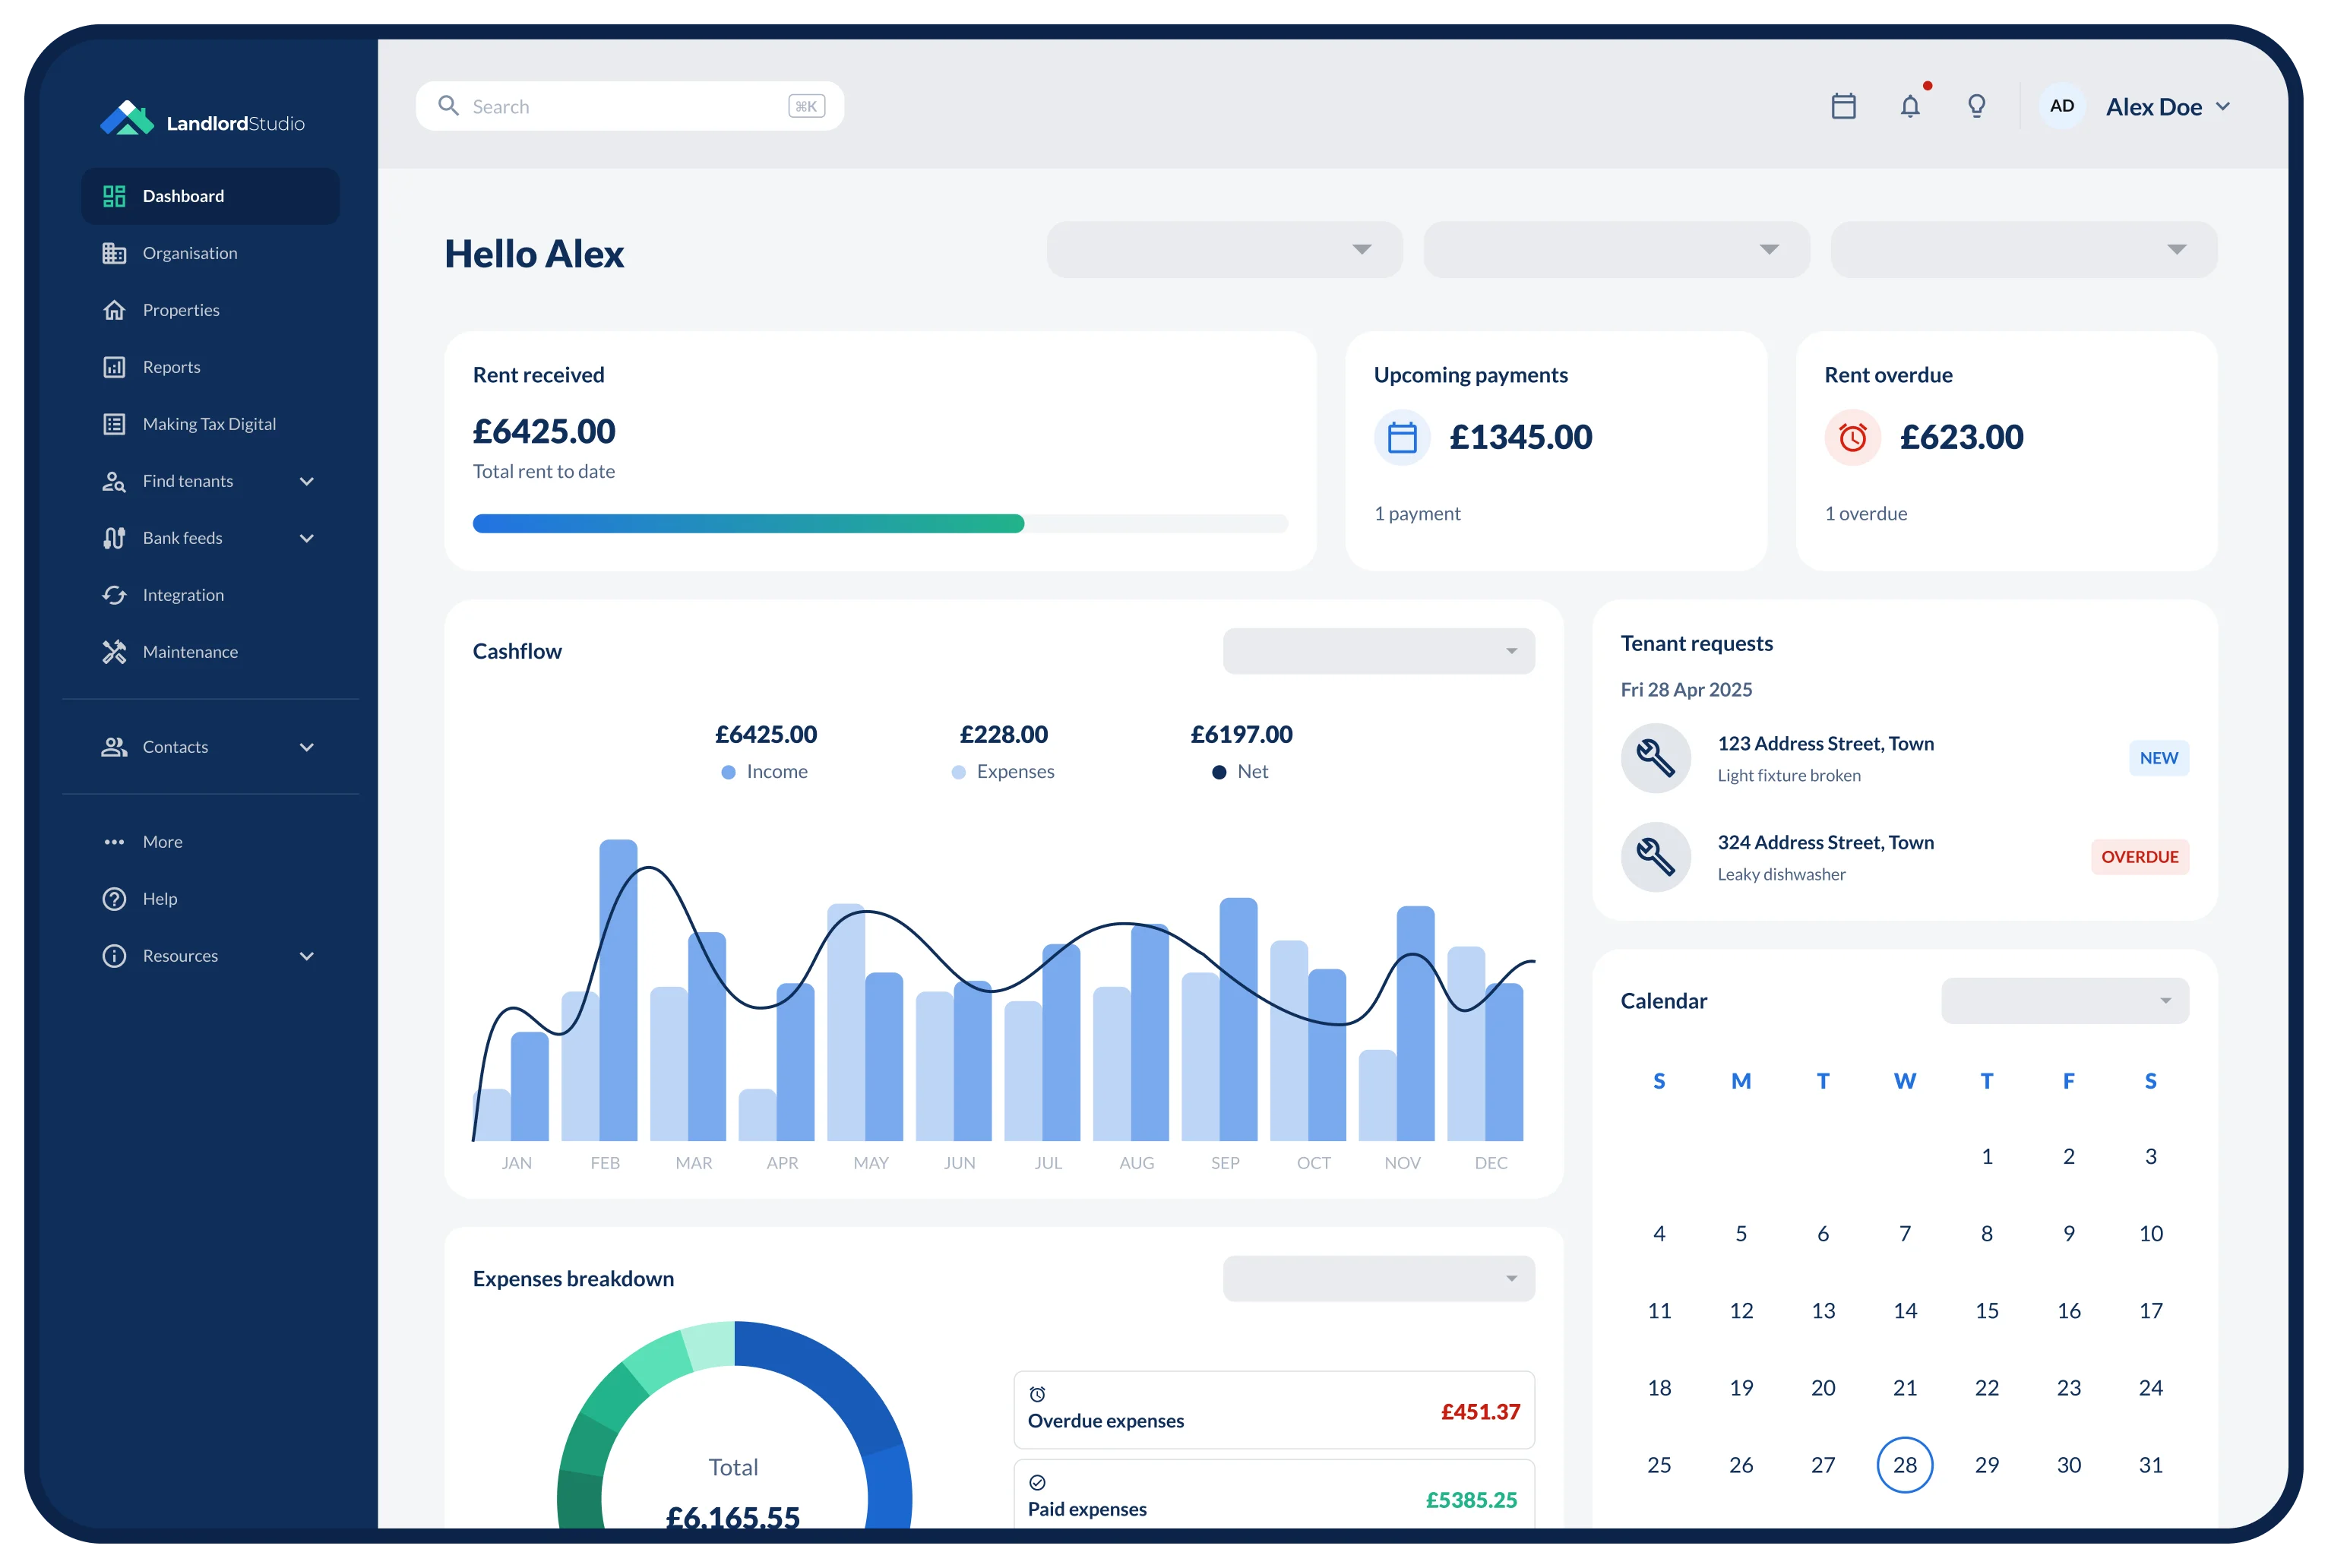
Use Landlord Studio to automatically track your rental income and expenses, calculate NOI in real-time, and monitor your property's cap rate throughout the year.
Try Free Calculator3 Real-World Cap Rate Calculation Examples
Understanding the cap rate formula is one thing—seeing it applied to actual properties is another. Here are three realistic scenarios showing how to calculate cap rate for different property types and investment strategies.
Example 1: Single-Family Rental (Starter Investor)
Scenario: You're considering purchasing a single-family home in a growing suburban market to rent out.
- Purchase Price: $200,000
- Monthly Rent: $1,500
- Annual Gross Income: $1,500 × 12 = $18,000
Annual Operating Expenses:
- Property taxes: $2,400
- Insurance: $1,200
- Property management (10%): $1,800
- Maintenance & repairs: $1,800
- HOA fees: $0
- Total Operating Expenses: $7,200
Calculation:
- Net Operating Income (NOI) = $18,000 - $7,200 = $10,800
- Cap Rate = ($10,800 ÷ $200,000) × 100 = 5.4%
What This Means: A 5.4% cap rate is typical for single-family rentals in stable, appreciating markets. While not exceptionally high, this property offers steady cash flow with good potential for appreciation. This cap rate is suitable for investors prioritizing long-term wealth building over immediate cash returns.
Example 2: Small Multifamily Property (Scaling Investor)
Scenario: You're looking to scale your portfolio with a 4-unit apartment building in a secondary market.
- Purchase Price: $500,000
- Monthly Rent per Unit: $1,250
- Annual Gross Income: $1,250 × 4 units × 12 months = $60,000
Annual Operating Expenses:
- Property taxes: $6,000
- Insurance: $2,500
- Property management (8%): $4,800
- Maintenance & repairs: $4,000
- Utilities (common areas): $1,200
- Vacancy allowance (5%): $3,000
- Total Operating Expenses: $21,500
Calculation:
- Net Operating Income (NOI) = $60,000 - $21,500 = $38,500
- Cap Rate = ($38,500 ÷ $500,000) × 100 = 7.7%
What This Means: A 7.7% cap rate represents solid cash flow for a small multifamily property. This is above average for many markets and indicates good income generation relative to the purchase price. Multifamily properties often command higher cap rates than single-family homes due to economies of scale and more predictable income streams.
Example 3: Commercial Mixed-Use Property (Advanced Investor)
Scenario: You're evaluating a mixed-use property with retail on the ground floor and apartments above in an urban location.
- Purchase Price: $1,200,000
- Annual Rent (Commercial): $45,000
- Annual Rent (Residential - 3 units): $75,000
- Annual Gross Income: $120,000
Annual Operating Expenses:
- Property taxes: $14,000
- Insurance: $4,500
- Property management (10%): $12,000
- Maintenance & repairs: $8,000
- Utilities: $3,500
- Vacancy allowance (3%): $3,600
- Total Operating Expenses: $45,600
Calculation:
- Net Operating Income (NOI) = $120,000 - $45,600 = $74,400
- Cap Rate = ($74,400 ÷ $1,200,000) × 100 = 6.2%
What This Means: A 6.2% cap rate for a commercial mixed-use property reflects moderate risk and stable returns. Mixed-use properties often have lower cap rates in prime urban locations due to appreciation potential and diversified income streams. The combination of commercial and residential tenants provides income stability while the urban location offers long-term value growth.
Key Takeaways from These Examples
- Property type matters: Single-family homes typically have lower cap rates (4-6%) while multifamily properties range higher (6-10%)
- Higher cap rates aren't always better: They often reflect higher risk or less desirable locations
- Operating expenses vary significantly: Always account for property management, maintenance, taxes, and insurance
- Don't forget vacancy: Even well-managed properties experience turnover
- Market context is crucial: Compare your cap rate to similar properties in the same area
Factors That Impact Cap Rates
The cap rate for rental properties is a crucial tool for making informed investment decisions. However, it's not perfect and there are numerous elements can impact the cap rate that should be considered when setting your cap rate target.
A few of these factors include:
- Location: Where the property is based can hold a substantial sway over the purchase price and rental rates.
- Market Size: Larger, more competitive markets tend to yield lower cap rates compared to smaller markets, where risks might be higher.
- Asset Stability: The projected stability of a property's value contributes significantly to cap rate considerations.
- Growth Potential: Properties with substantial growth potential within burgeoning markets can impact cap rates.
- Capital Investment: The amount of capital invested directly influences the Net Operating Income (NOI), thereby affecting the cap rate.
These factors, amongst others, wield significant influence over the cap rate and risk profile of an investment. Investors should consider as many factors as possible before making any investment decisions.
What Is A Good Cap Rate?
For a US single-family rental, a good cap rate is one at or above the current national average of 7.3%, adjusted for your local market and the condition of the property. Single-family rental cap rates averaged 7.3% in the fourth quarter of 2025, up from a low of 5.4% in late 2021, according to Arbor Realty Trust's Single-Family Rental Investment Trends Report Q1 2026. A 5% cap rate in a high-price coastal market and a 9% cap rate in a secondary Midwest market can both be good deals, because cap rate prices in risk and expected appreciation as well as income.
Some investors won't touch anything with a cap rate of less than 8%. Others aim for higher still, looking for double figures hoping to achieve a maximum ROI.
However, it depends on how comfortable you are with risk, your long-term goals, and of course the location that you're investing in. For example, if you wanted to invest in San Francisco you simply won't achieve a 10% cap rate no matter how hard you look.
People who don't want excessive risk but still want to achieve a respectable ROI will often look for a cap rate of between 4-6%. This range offers a reasonably good yield and enough stability for you not to feel nervous about potential cash flow issues.
Cap Rate Benchmarks by Property Type
Cap rates vary significantly by property type, location, and condition. Use this table as a general guide for evaluating whether a cap rate is in line with market standards.
| Property Type | Typical Cap Rate Range | Risk Level | Example Markets |
|---|---|---|---|
| Class A Multifamily | 4% - 6% | Low | NYC, San Francisco, Seattle |
| Class B Multifamily | 6% - 8% | Moderate | Austin, Denver, Portland |
| Class C Multifamily | 8% - 12% | Higher | Secondary/tertiary markets |
| Single-Family Rentals | 5% - 10% | Varies | Market-dependent |
| Commercial Office | 6% - 9% | Moderate | Major metros |
| Retail | 6% - 8% | Moderate-High | Suburban areas |
| Industrial/Warehouse | 5% - 7% | Low-Moderate | Logistics hubs |
Note: Cap rates vary significantly by location, property condition, and market cycle. Always compare to local comparable properties and consider market-specific factors. These ranges represent national averages and should be used as general guidelines, not absolute benchmarks.
What is a good cap rate for a single-family rental or small multifamily?
A single-family rental at or near the 7.3% national average is performing in line with the market, and multifamily is normally judged tighter because it is priced closer to institutional standards. Single-family rental cap rates sat 160 basis points above multifamily cap rates in the fourth quarter of 2025, per Arbor Realty Trust's Q1 2026 report, so a duplex trading at 6% is not automatically worse value than a rental house at 7.5%. The two are priced by different pools of buyers.
Read the benchmark ranges in the table above residential-first. The same figures as a list:
- Single-family rentals: 5% to 10%, market-dependent. The sourced national average was 7.3% in Q4 2025.
- Class C multifamily: 8% to 12%, higher risk, secondary and tertiary markets.
- Class B multifamily: 6% to 8%, moderate risk, markets such as Austin, Denver and Portland.
- Class A multifamily: 4% to 6%, low risk, primary metros such as New York, San Francisco and Seattle. This is institutional pricing and rarely relevant to a private landlord.
If you are buying a rental house rather than a commercial building, the single-family row is the one that matters. Cap rate is only meaningful against like-for-like comparables, so compare a three-bedroom rental house to other three-bedroom rental houses in the same zip code, never to an office building or a Class A apartment block.
Understanding the Risk-Return Relationship
Notice the inverse relationship between cap rate and risk level:
- Lower cap rates (4-6%): Typically found in prime locations with stable tenants, strong appreciation potential, and lower risk. Investors accept lower cash flow in exchange for stability and growth.
- Moderate cap rates (6-8%): Balanced approach with decent cash flow and moderate appreciation. Most common range for mainstream investors.
- Higher cap rates (8%+): Usually indicate higher risk properties—less desirable locations, older buildings, or markets with economic challenges. Higher cash flow compensates for increased risk and potentially lower appreciation.
Your investment strategy should dictate your target cap rate range: Conservative wealth builders might prefer 4-6%, balanced investors target 6-8%, and value-add specialists seek 8%+ properties they can improve.
How Market Conditions Affect Cap Rates
Cap rates aren't static—they fluctuate based on market dynamics and economic conditions.
Cap Rates Rise (Properties Become More Affordable) When:
- Interest rates increase (higher borrowing costs reduce demand)
- Economic uncertainty grows (investors demand higher returns for risk)
- Local market weakens (job losses, population decline)
- Property supply exceeds demand (overbuilding)
Cap Rates Fall (Properties Become More Expensive) When:
- Interest rates decrease (cheap money increases demand)
- Economic confidence strengthens (investors accept lower yields)
- Markets are "hot" (strong job growth, population influx)
- Demand exceeds supply (housing shortage)
What This Means for Investors: A "good" cap rate in 2020 (interest rates near 0%) might be 4-5%, while a "good" cap rate in 2024 (interest rates at 7%+) might be 6-8%. Always compare to current market conditions, not historical averages.
Related: Free Rental Yield Calculator
How To Use Cap Rate To Assess Rental Property
It's all very well to crunch the numbers and get your estimated cap rate. But if you don't know what to look for, know what a good cap rate is, and know how to compare properties then calculating your cap rate is a largely pointless exercise.
Generally speaking, a higher cap rate is a riskier investment but is also likely a more profitable one.
It's important to note though that you can't simply set a blanket target cap rate, as cap rates will vary broadly in different locations. As such, you should run a cap rate analysis on several other similar rental properties in the area to give yourself a benchmark.
The target cap rate you look for has to take into account key factors, such as location, demand, and economic stability of the area (for example, how available are jobs?).

When Should You Not Use The Capitalization Rate?
Capitalization rates serve as a powerful tool for real estate investors to assess potential rental property investments. However, as mentioned already, it's not without its flaws and limitations. A few situations where applying the cap rate metric might be limited include:
- Inconsistent Income History: If a property, such as an apartment building used for short-term vacation rentals, lacks a consistent income history, the cap rate formula might not effectively predict its investment value. In such cases, employing a cash flow model could offer a more accurate estimation of returns.
- Financing Methods: The cap rate formula doesn't generally take into account leverage. When considering a mortgage to finance an investment, the cap rate may not provide the most suitable metric.
- Long-Term Uncertainty: Cap rates hinge on the assumption of long-term income stability. However, they fail to consider potential future risks like depreciation or market shifts that could lead to income fluctuations.
- Renovations: The cap rate doesn't take into account any potential additional investment that might be made into the property. If you're planning to renovate the property to increase its value and rental rates the cap rate may not be the best metric.
Cap Rate vs. Other Real Estate Investment Metrics
Cap rate is a powerful tool for evaluating rental properties, but it shouldn't be used in isolation. Understanding how cap rate compares to other investment metrics helps you make more informed decisions and avoid common analysis pitfalls.
Quick Comparison: Cap Rate and Alternative Metrics
| Metric | What It Measures | Best Used For | Key Difference from Cap Rate |
|---|---|---|---|
| Cap Rate | Unlevered return on property | Comparing similar properties | Independent of financing |
| Cash-on-Cash Return | Return on actual cash invested | Evaluating leverage impact | Includes mortgage payments |
| ROI (Return on Investment) | Total return including appreciation | Long-term performance analysis | Includes equity buildup and appreciation |
| Gross Rent Multiplier (GRM) | Price relative to gross income | Quick initial screening | Doesn't account for expenses |
| Internal Rate of Return (IRR) | Time-adjusted total return | Multi-year investment analysis | Factors in timing of cash flows |
Cap Rate vs. Cash-on-Cash Return
This is one of the most common points of confusion for new real estate investors.
Cap Rate: Measures property performance independent of how you financed it
- Formula: (NOI ÷ Property Value) × 100
- Ignores mortgage payments completely
- Great for comparing different properties on equal footing
Cash-on-Cash Return: Measures return on your actual out-of-pocket investment
- Formula: (Annual Cash Flow ÷ Total Cash Invested) × 100
- Includes mortgage payments (PITI)
- Shows your real return after debt service
Example Comparison:
Property Details:
- Purchase Price: $200,000
- Down Payment (20%): $40,000
- NOI: $10,800
- Annual Mortgage Payment: $7,200
- Annual Cash Flow (after mortgage): $3,600
Cap Rate: ($10,800 ÷ $200,000) × 100 = 5.4%
Cash-on-Cash Return: ($3,600 ÷ $40,000) × 100 = 9%
Notice how the cash-on-cash return (9%) is significantly higher than the cap rate (5.4%) because leverage amplifies returns. This is why investors use mortgages—to boost their actual returns on invested capital.
When to use each:
- Use Cap Rate: When comparing properties, analyzing all-cash scenarios, or evaluating property fundamentals
- Use Cash-on-Cash: When you're using financing and want to know your true return on invested capital
Cap Rate vs. Total ROI
While cap rate measures annual operating income, ROI captures your total return including appreciation and equity buildup.
Cap Rate Limitation: Only measures current operating income, ignores future value growth
Total ROI Includes:
- Annual cash flow (what cap rate measures)
- Property appreciation (market value increase)
- Mortgage principal paydown (equity buildup)
- Tax benefits (depreciation deductions)
Example: A property with a 5% cap rate might deliver 15%+ total annual ROI when you factor in 3-4% appreciation and mortgage paydown.
The Takeaway: In appreciating markets, investors often accept lower cap rates (4-6%) because the total ROI remains attractive. In flat or declining markets, you need higher cap rates (8%+) to compensate for lack of appreciation.
When to Use Cap Rate
Cap rate is most valuable in these situations:
- Comparing similar properties: Evaluating multiple investment options in the same market
- Commercial real estate analysis: Industry standard for multifamily, retail, and office properties
- Quick investment assessment: Fast way to evaluate if a deal warrants deeper analysis
- Market benchmarking: Understanding typical returns in different markets or property classes
- All-cash scenarios: When not using financing or want to compare properties without debt variables
The Best Approach: Use Multiple Metrics
Professional real estate investors don't rely on a single metric. Instead, they use a combination:
- Screen with GRM: Quickly filter out obviously poor deals
- Analyze with Cap Rate: Evaluate property fundamentals and compare to market
- Project with Cash-on-Cash: Understand your actual returns with financing
- Forecast with Total ROI/IRR: Model long-term value creation
Each metric tells you something different about the investment. Cap rate shows you the property's earning power, cash-on-cash shows you the leverage effect, and total ROI shows you the complete wealth-building picture.
⚠️ Important Reminder: No single metric can tell you if a property is a good investment. Cap rate, cash-on-cash return, and ROI are all tools in your analysis toolkit. Use them together, along with thorough due diligence on the property, neighborhood, and market conditions, to make informed investment decisions.
How To Save Time and Improve Portfolio Profitability
Whatever your goals are, whether it's simply to generate a little income on the side, to build a nest egg for retirement, or you want to build wealth and achieve financial freedom, the most important aspect is time.
The more time you're managing your rentals the less time you have to scale, travel, or spend time with family and friends.
Modern real estate investors then are always looking for software and automation tools to help them gain control over their portfolios, save time, and improve operational efficiencies.

Landlord Studio, allows users to easily track income and expenses via their mobile device or desktop. Use time-saving features such as smart scan receipts which allows you to digitize receipts at the point of sale and the software automatically extracts the receipt data and creates the expense for you, and connect your bank feeds to view and reconcile transactions in real-time.
Additional features include property maintenance management, tenant screening, and online rent collection, which enables tenants to automate their rent payments. All income collected through online rent collection is automatically tracked in our income tracker. Automate tenant communications, set reminders for yourself, and more.
Cap Rate In Real Estate: Final Words
Every investor has different circumstances and goals and so you need to adapt your strategy accordingly. A good cap rate for some might not be so good for others. There are numerous determining factors to consider before you make an investment decision. The cap rate is only one metric that you can use to get a quick assessment of a prospective rental property.
You Might Like
- About Your Rental Property Profit and Loss Statement
- What is Net Cash Flow and How Do You Calculate It?
- Understanding Cash-on-Cash Return vs Cap Rate for Your Rental Property Investment
- Cap Rate vs ROI: What's the Difference and Which one Should Landlords be Tracking?
- 11 Real Estate Investing Metrics that Investors Need to Know
Cap Rates & Cap Rate Formula FAQs
What is the exact formula for cap rate?
The cap rate formula is: (Net Operating Income ÷ Property Value) × 100
This calculation gives you the capitalization rate as a percentage, representing the expected annual return on your real estate investment before financing costs.
Breaking it down:
- Net Operating Income (NOI) = Annual rental income minus all operating expenses (property taxes, insurance, management, maintenance, etc.)
- Property Value = Current market value or purchase price of the property
- Multiply by 100 = Converts the decimal to a percentage
Example: A property with $12,000 annual NOI and a $200,000 value has a cap rate of 6% ($12,000 ÷ $200,000 × 100 = 6%).
How do I calculate cap rate if I don't know the property value?
If you don't have an exact property value, you have several options:
- Use comparable sales: Research recent sales of similar properties in the same neighborhood. Look for properties with similar size, age, condition, and features.
- Get a professional appraisal: Hire a licensed appraiser for an accurate market value assessment (typically costs $300-500).
- Use online estimates: Tools like Zillow Zestimate, Redfin Estimate, or Realtor.com provide free estimated values (though these can be 5-10% off actual value).
- Consult a real estate agent: Local agents can provide a Comparative Market Analysis (CMA) showing what similar properties sold for recently.
- For purchase analysis: Use the asking price or your intended offer price as the property value in your cap rate calculation.
Important: For the most accurate cap rate, use current market value rather than outdated assessments or your original purchase price from years ago. Property values change, and an accurate cap rate requires up-to-date valuations.
What's the difference between cap rate and cash-on-cash return?
Cap rate and cash-on-cash return measure different aspects of your investment:
Cap Rate measures the property's return independent of financing:
- Formula: (NOI ÷ Property Value) × 100
- Ignores mortgage payments completely
- Best for comparing properties on equal footing
- Useful for all-cash purchase analysis
Cash-on-Cash Return measures your return on actual cash invested:
- Formula: (Annual Cash Flow ÷ Total Cash Invested) × 100
- Includes mortgage payments
- Reflects the impact of leverage (using debt)
- Shows your real return after debt service
Example:
- $200,000 property with $10,800 NOI has a 5.4% cap rate
- If you put down $40,000 (20%) and have $7,200 annual mortgage payment:
- Cash flow after mortgage = $3,600 ($10,800 - $7,200)
- Cash-on-cash return = $3,600 ÷ $40,000 = 9%
Notice the cash-on-cash return (9%) is much higher than the cap rate (5.4%) because leverage amplifies returns. Most investors use both metrics—cap rate to evaluate the property itself, and cash-on-cash to evaluate their personal return on invested capital.
Learn more about calculating cash-on-cash return for rental properties.
Can cap rate be negative, and what does that mean?
Yes, cap rate can be negative, and it's always a red flag for investors.
A negative cap rate occurs when: Operating expenses exceed rental income, resulting in negative Net Operating Income (NOI).
Example of Negative Cap Rate:
- Annual Rental Income: $15,000
- Operating Expenses: $18,000
- NOI = $15,000 - $18,000 = -$3,000
- Property Value: $200,000
- Cap Rate = (-$3,000 ÷ $200,000) × 100 = -1.5%
What this means: The property is losing money operationally—even before mortgage payments. You're subsidizing the property's operations out of pocket every month.
When negative cap rates might occur:
- Vacancy-plagued properties (insufficient rental income)
- Severely underperforming rentals (rent too low for market)
- High-expense properties (excessive taxes, insurance, or maintenance)
- Renovation projects (temporarily non-income producing)
- Speculative land holdings (no income, only expenses)
Is a negative cap rate ever acceptable? Only in specific scenarios:
- Value-add investments: You're renovating to increase NOI and make it positive
- Appreciation plays: You expect significant property value increase to offset negative cash flow (risky strategy)
- Development projects: Temporary negative cash flow during construction/lease-up phase
For traditional buy-and-hold rental investors, a negative cap rate indicates a property that is not viable without significant changes. Avoid these properties unless you have a clear, executable plan to turn the NOI positive.
How often should I recalculate my property's cap rate?
You should recalculate your property's cap rate annually at minimum, and also whenever significant changes occur.
Recommended Recalculation Schedule:
Annually (at minimum):
- Property values change with market conditions
- Operating expenses tend to increase over time
- Rent levels may adjust with market dynamics
- Helps you track investment performance over time
Recalculate immediately when:
- Rent increases: Raised rent significantly (increases NOI, improves cap rate)
- Major expense changes: Property taxes reassessed, insurance premium jumps, or completed major repairs
- Market shifts: Local real estate market heats up or cools down substantially
- Considering sale: Want to understand current return to evaluate if you should hold or sell
- Refinancing: Evaluating whether to refinance based on property's current performance
- Value-add completion: Finished renovations that improved property value or rental income
Why regular recalculation matters:
Your property's cap rate from 5 years ago tells you nothing about its performance today. A property purchased at an 8% cap rate might now be at 6% (due to property appreciation) or 10% (due to market decline). Understanding your current cap rate helps you:
- Make informed hold-vs-sell decisions: If cap rate compressed to 4% due to appreciation, it might be time to sell and redeploy capital
- Benchmark against alternatives: Compare your current return to other available investments
- Identify problems early: Declining cap rate (from expense growth) signals operational issues to address
- Plan portfolio strategy: Understand which properties are still performing well and which need attention
Pro tip: Use property management software like Landlord Studio to automatically track income, expenses, and NOI throughout the year. This makes annual cap rate recalculation as simple as entering your current property value estimate. Try our free cap rate calculator.
What is a Good Cap Rate?
A good cap rate for an investment property typically falls within the range of 4% to 10%. However, pinpointing the exact figure hinges on the property's location and the necessary rate of return to deem the investment financially viable. Some areas with higher purchase prices, for example, might achieve lower cap rates in general but cash flow better and achieve better long term capital gains.
What is a Bad Cap Rate?
There's no single number that can be used as a bad cap rate, just as there aren't any universal numbers for a good cap rate. However, one way to look at it is a bad cap rate would be anything that is lower than the cap rate of a similar property. Again, keep in mind that the property with a lower cap rate might possess long-term potential if enhancements can be made to reduce expenses or boost income.
What is the purpose of the cap rate calculation?
The cap rate helps real estate investors evaluate whether a property is a good investment by measuring its income potential relative to its price. It's especially useful in commercial real estate for comparing properties beyond surface-level factors like aesthetics or location.
Is a Higher or Lower Capitalization Rate Better?
Generally, the capitalization rate can be viewed as a measure of risk. A higher cap rate suggests greater investment risk (but higher profits), while a lower cap rate indicates lower risk (with lower profits). The investor's risk tolerance and profile significantly shape whether a higher or lower cap rate is perceived as favorable.
What Is the Difference Between the Capitalization Rate and Return on Investment?
Return on investment forecasts the potential returns an investment might yield over a defined period. Whereas, the capitalization rate reveals the current return of an investment or its expected yield.
Is Cap Rate the Same as ROI?
No, though they may seem similar cap rate doesn't directly equate to ROI. Return on investment (ROI) is a versatile metric that assesses the returns relative to the initial investment across various scenarios. Cap rate operates as a percentage figure indicating a property's potential to generate a strong ROI.
What is the Purpose of the Cap Rate Calculation?
In real estate, the cap rate calculation serves as a crucial tool aiding investors in assessing the viability of a deal. It enables them to gauge a property's value and potential returns, making it easier to compare like-for-like properties, and aiding in informed decision-making when pursuing real estate opportunities.
Why is a Real Estate Cap Rate Important for Property Investors?
Much like a savvy shopper aiming for the best price, real estate investors are looking for properties that promise the best cash flow. The cap rate formula becomes instrumental in their decision-making, enabling them to discern which property holds the potential to make the most profit.
What is the Difference Between Cap Rate and Yield?
While the yield percentage of a property is calculated by dividing its annual income by its total cost, the cap rate measures income divided by the property's price or value.
Unlike the cap rate, yield doesn't solely reflect cash flow. Yield, often termed as a rate of return, encompasses broader considerations like leverage and rental property tax deductions, and can help investors get a more comprehensive evaluation of a property's overall cost.
How do Cap Rates Vary Between Urban and Suburban Areas?
Cap rates are dependent on real estate prices, along with rental rates, both opf which are influenced by broad economic factors. Consequently, distinct regions exhibit differing cap rates determined by the local economy, property values, and average rental rates. As such, when comparing rental property cap rates it's important to only compare similar properties in comparable neighborhoods. There's no point comparing a New York City property to one in small-town Ohio.
What are the Disadvantages of Using Cap Rate to Analyze an Investment?
The cap rate serves as a quick way to assess a property's performance. It however, only looks at current data and doesn't take into account local investment in the area, potential growth of the housing market, or renovations the investor makes. By only looking at cap rate then you could potentially miss hidden gems.
What is Cap Rate Compression?
The capitalization rate, derived from dividing the net operating income by the purchase price, defines the stability of real estate assets. However, real estate values aren't always constant; they fluctuate based on factors like vacancy rates, neighborhood dynamics, and market conditions. When a property's value rises, dividing the annual net income by the purchase price results in a decreased percentage, leading to a lower cap rate. This phenomenon is termed cap rate compression.
Debate exists among real estate investors regarding whether cap rate compression indicates higher or lower risk. On one side, it signifies the property's ascension as an appreciating asset class. Conversely, it can pose challenges for new investors aiming to enter the market, potentially necessitating cash purchases if securing favorable lending becomes challenging amidst cap rate compression.
What is a 7.5% cap rate?
A 7.5% cap rate means the property's annual net operating income equals 7.5% of its value. On a $250,000 single-family rental that is $18,750 of NOI a year, after operating expenses and before any mortgage payment. Against the 7.3% national average for single-family rentals in the fourth quarter of 2025, a 7.5% cap rate is roughly market rate rather than a bargain.
What does a 3% cap rate mean?
A 3% cap rate means net operating income is only 3% of the property's value, so $9,000 a year on a $300,000 house. That sits well below the 7.3% national average for single-family rentals recorded in the fourth quarter of 2025. The buyer is either accepting very thin income in exchange for expected appreciation in a high-price market, or overpaying. Check the expense assumptions first, because an understated vacancy or maintenance figure is the most common reason a cap rate comes out this low.
What is the 7% rule in real estate?
There is no established 7% rule in US real estate. Landlords asking about it are usually thinking of one of two things: the 1% rule, which says monthly rent should be at least 1% of the purchase price, or a personal minimum target of a 7% cap rate. Neither is a standard. Cap rate is the figure you can actually measure, and the 7.3% national average for single-family rentals in Q4 2025 is a more useful reference point than any rule of thumb.


About Landlord Studio

Landlord Studio is an easy to use property management and accounting software designed for landlords.
Find and screen tenants, collect rent online, track income and expenses, run reports, and more - all for free.
Create your FREE account with Landlord Studio today.

From finding tenants to filing taxes. Reduce vacancies and maximize your portfolio ROI with software designed for you.
Get started for free