LTT Calculator

Work out the Land Transaction Tax on a property in Wales. It checks whether the higher rates apply from what you'll own after buying, covers the £225,000 nil-rate band where the main rates apply, and shows the non-residential option for six or more dwellings.
Illustration of two blue houses with a tree between them

Land Transaction Tax (LTT) replaces stamp duty in Wales and is collected by the Welsh Revenue Authority. If you'll own more than one residential property after buying, a separate table of higher rates usually applies.

Six or more dwellings in one transaction can be treated as non-residential, and this calculator shows that option. Mixed-use purchases use non-residential rates.
Count property anywhere in the world, including part shares and property your spouse or civil partner owns. Buying jointly? Answer yes if any buyer will.
Haven't sold your old main home yet? The higher rates usually apply now, with a refund if you sell it within 3 years.
Estimate only. Rates checked November 2026 against the Welsh Government and reviewed after each Welsh budget. Covers freehold residential, mixed-use and six-or-more-dwelling purchases. It simplifies the higher-rates ownership test and does not cover trusts, leases, linked transactions, multiple dwellings relief or other reliefs. File the return and pay LTT to the Welsh Revenue Authority within 30 days, beginning with the day after completion (or another effective date where that applies). Not tax advice.

How to calculate LTT on a buy-to-let

Work out which table applies, then tax each slice of the price at its rate and add them up. A buy-to-let bought by someone who'll own more than one residential property uses the higher-rates table from the first pound.
Buying in England? Use our stamp duty calculator →
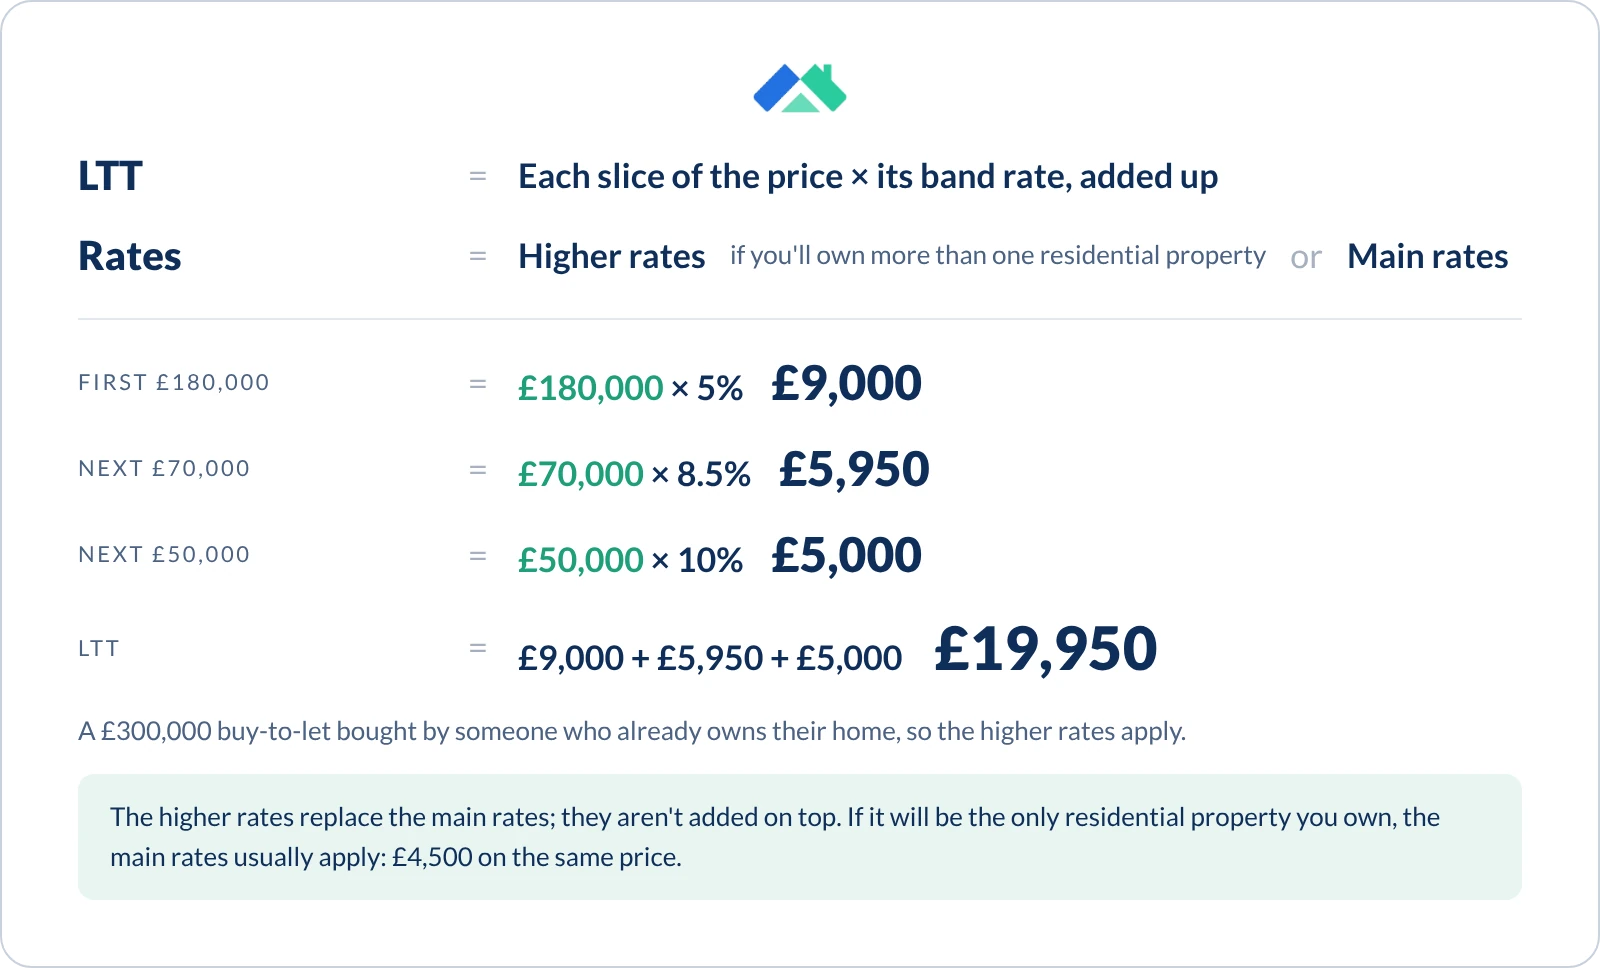
LTT formula with a worked example: a £300,000 buy-to-let at the higher rates pays £9,000 + £5,950 + £5,000 = £19,950
Step 1

Pick the right table

Use the higher rates if you'll own more than one residential property after buying and the price is £40,000 or more, unless you're replacing your main home and the old one is sold by completion. Otherwise use the main rates.

Step 2

Split the price into bands

Higher rates: up to £180,000, then to £250,000, £400,000, £750,000, £1.5 million and above.

Step 3

Tax each slice and add them up

5%, 8.5%, 10%, 12.5%, 15% and 17%. Each rate applies only to its own slice. The total is your bill.

Worked example

‍

A £300,000 buy-to-let in Wales, bought by someone who already owns their home, so the higher rates apply.

‍

LTT = (£180,000 × 5%) + (£70,000 × 8.5%) + (£50,000 × 10%)

‍

= £9,000 + £5,950 + £5,000 = £19,950

Calculator icons

Other calculators you might be interested in
Landlord Studio icon

LBTT Calculator

Work out Land and Buildings Transaction Tax in Scotland, including the 8% Additional Dwelling Supplement.

Landlord Studio icon

Stamp Duty Calculator

Work out stamp duty in England and Northern Ireland, including the 5% surcharge on additional homes.

Landlord Studio icon

Buy-to-Let Mortgage Calculator

Estimate monthly payments and check whether your rent passes the lender's ICR stress test.

How LTT works on a buy-to-let

Icon of a document with a pound sign

Higher rates from the first pound

Wales doesn't add a surcharge. If you'll own more than one residential property after buying and the price is £40,000 or more, a separate table of higher rates replaces the main rates, starting at 5% on the first £180,000. That includes buying a new main home before you've sold the old one.

‍

Buying your first and only residential property to let out? The main rates usually apply. Companies buying residential property usually pay the higher rates.

Icon of a rising data chart with a magnifying glass

Nothing to pay on the first £225,000

Where the main residential rates apply, no LTT is payable on the first £225,000. Then it's 6%, 7.5%, 10% and 12% on the slices above.

‍

There's no separate first-time buyer relief in Wales.
Illustration of a landlord reviewing a rental performance dashboard on a phone

Why should you use our LTT calculator?

  • Works out whether the higher rates apply from what you'll own, not just what you're buying
  • Covers replacing your main home, including the refund if you haven't sold the old one yet
  • Shows the non-residential option for six or more dwellings, and mixed-use rates
  • Shows the band-by-band working, not just a total
  • Free, fast and no sign-up

FAQs

How is Land Transaction Tax calculated?

Plus Icon

LTT is charged in slices. At the main residential rates you pay nothing on the first £225,000, 6% on the part up to £400,000, 7.5% to £750,000, 10% to £1.5 million and 12% above that.

A £300,000 home at the main rates comes to £4,500.

How much LTT do I pay on a buy-to-let?

Plus Icon

It depends on what else you own. If you'll own more than one residential property after buying, the higher rates replace the main rates: 5% up to £180,000, 8.5% to £250,000, 10% to £400,000, 12.5% to £750,000, 15% to £1.5 million and 17% above that. On a £300,000 buy-to-let that's £19,950.

If it will be the only residential property you own, the main rates usually apply even though you're letting it out, which on £300,000 is £4,500.

When do the LTT higher rates apply?

Plus Icon

Usually when you buy a residential property for £40,000 or more and, at the end of that day, you'll own more than one residential property anywhere in the world. Property your spouse or civil partner owns counts, and on a joint purchase the higher rates apply if any buyer meets the test.

They also usually apply if you buy a new main home before selling your old one, and companies buying residential property of £40,000 or more usually pay them too.

Can I get a refund of the LTT higher rates?

Plus Icon

Usually, if you bought a new main home before selling your old one. Sell your previous main home within 3 years of buying the new one and you can apply to the Welsh Revenue Authority for a refund of the difference.

Is there first-time buyer relief in Wales?

Plus Icon

No. Wales has no separate first-time buyer relief. Where the main residential rates apply, no LTT is payable on the first £225,000, so many first homes have no LTT to pay at all.