



Read summarised version with:

ChatGPT

Gemini

Claude

Grok

Add as preferred on Google
For many of the UK’s 2.8 million-plus landlords, the end of the tax year can bring a familiar sense of dread.
Sifting through a year's worth of receipts, reconciling bank statements, and facing a potentially hefty tax bill is hardly the reason most people get into property investment.
But what if you could legally reduce that bill?
The term ‘landlord loopholes’ might sound illicit, but in reality, it’s about smart, informed tax planning. It’s about understanding the system and making it work for you.
With a bit of knowledge and foresight, you can legally pay less tax on your buy-to-let portfolio. Here are five of the highest-value ways to do just that.
1. Become an Expense-Claiming Master
This is the absolute cornerstone of reducing your rental property tax bill, yet it’s surprising how many landlords leave money on the table. Every legitimate expense you incur in the running of your property business can be deducted from your rental income, reducing your overall profit and, therefore, your tax liability.
Beyond the obvious costs like letting agent fees and landlord insurance, there’s a whole host of expenses you should be meticulously tracking mileage, home office costs, professional fees (accountant, legal fees, etc.), software subscriptions, and any relevant training and courses you have taken.
The key is to keep immaculate records. A shoebox of faded receipts won’t cut it, especially now Making Tax Digital (MTD) for Income Tax is in force. Digital record-keeping is essential.
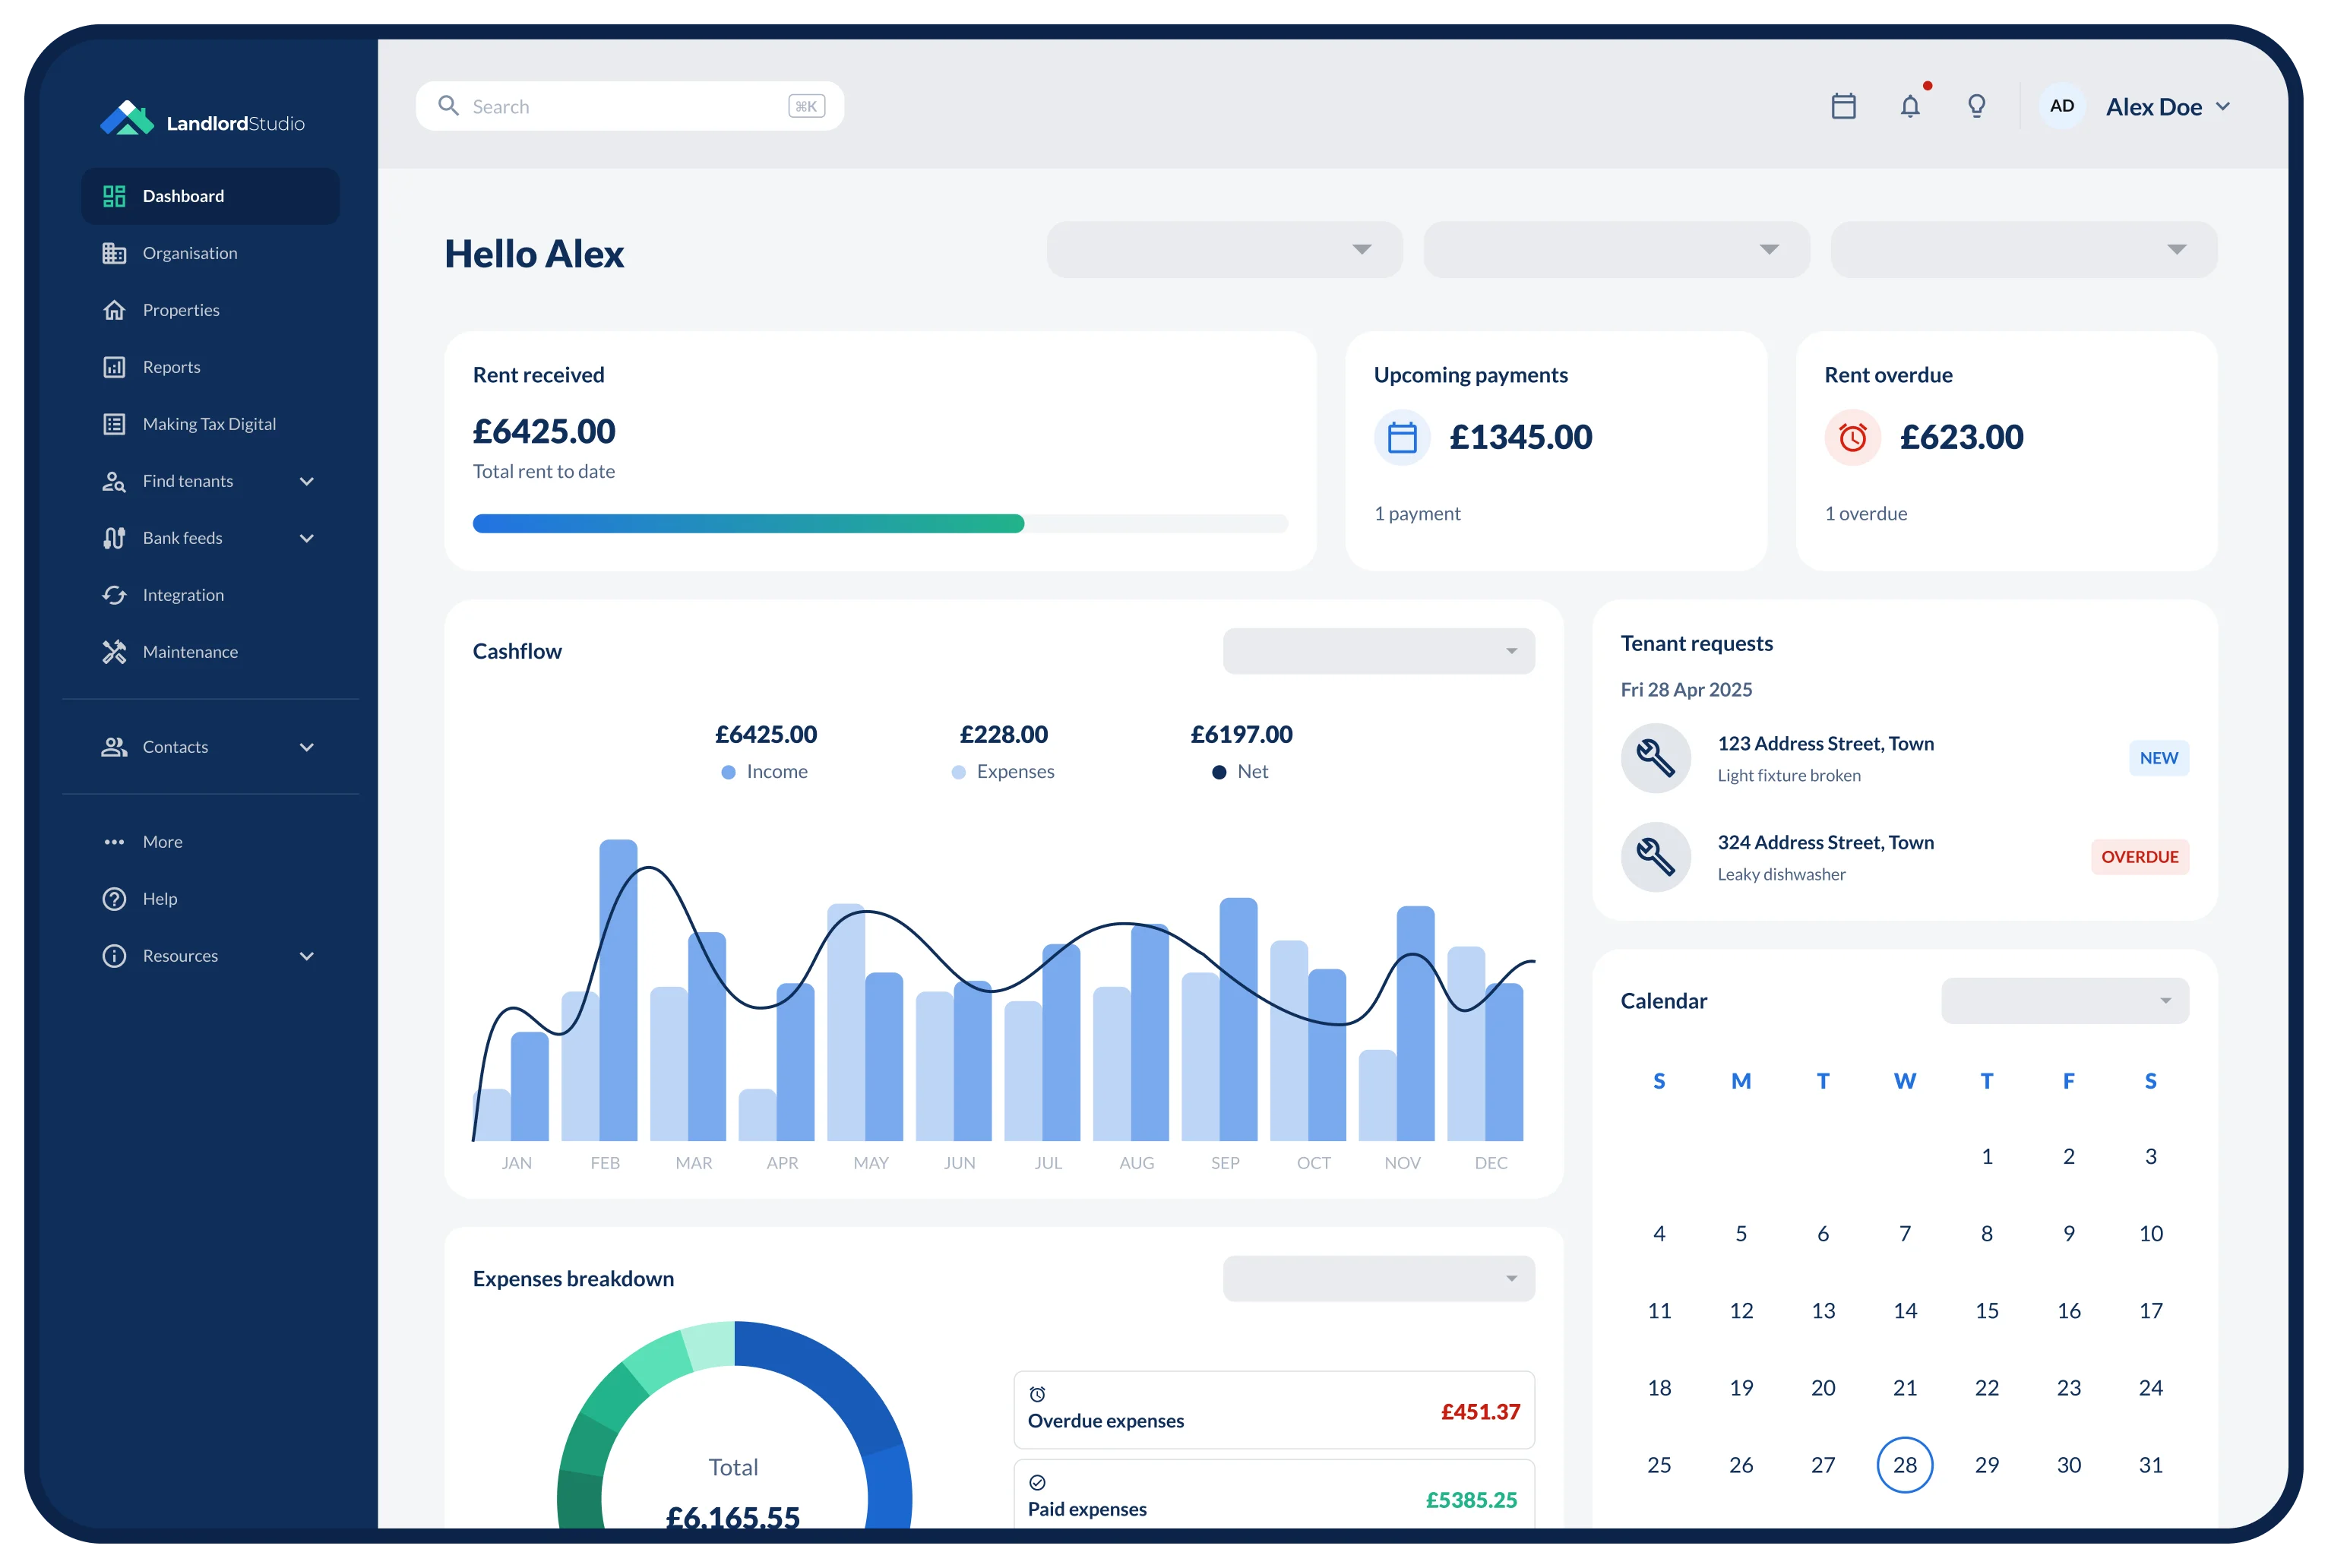
Leveraging purpose-built digital record-keeping software like Landlord Studio can help you stay on top of your finances while ensuring you are MTD compliant.
2. Play the Capital Gains Game
Thinking about how to sell your buy-to-let property? This is where Capital Gains Tax (CGT) comes into play.
CGT is the tax you pay on the profit you make when you sell an asset that has increased in value. For property, the rates are higher than for other assets (18% for basic-rate taxpayers and 24% for higher-rate taxpayers).
However, there are several ways to minimise the impact.
First, everyone has an annual CGT allowance, which is the amount of profit you can make tax-free each year. This is currently £3,000. If you jointly own the property with a spouse or partner, you can combine your allowances, effectively doubling the tax-free portion of your gain.
Second, you can deduct a range of costs from your capital gain to reduce the taxable amount. These include:
- The original stamp duty paid when you purchased the property.
- Solicitor’s and estate agent’s fees from both buying and selling.
- The cost of any capital improvements made to the property during your ownership – think extensions, new kitchens, or loft conversions. Note that these are different from day-to-day repairs.
Planning the timing of a sale can make all the difference here. If you are a higher-rate taxpayer, could you delay the sale until a year when your income might be lower, dropping you into the basic rate for CGT? It’s worth mulling over.

3. The Limited Company Question
One of the most debated topics among landlords is whether to hold property personally or within a limited company.
This became a particularly hot topic after changes in 2017 restricted the amount of mortgage interest relief individual landlords could claim. Now, individual landlords only receive a 20% tax credit on their mortgage interest payments. Limited companies, however, can still deduct 100% of their mortgage interest as a business expense.
While the ongoing tax benefits are clear for higher-rate taxpayers, the process of moving existing properties into a company structure is complex and can trigger significant tax charges like Stamp Duty and Capital Gains Tax. It is not a simple loophole.
As one user on the popular r/UKLandlords Reddit forum wisely cautions:
"You'll be inundated with people telling you can transfer to limited company without any major tax ramifications. They are wrong... You need to speak to a IFA to assess YOUR financial situation."
This advice highlights a really important point: while the limited company structure offers advantages, it's not a universal solution and the setup requires careful financial and tax planning.
For landlords with larger, leveraged portfolios, it can be a powerful tool to pay less tax, but only when executed with professional guidance.
4. Strategic Spending on Property Maintenance
The distinction between a repair and an improvement is a critical one in the eyes of HMRC.
- A repair is work that restores an asset to its previous condition, such as repainting a room in the same colour, fixing a leaky roof, or replacing a broken window with a modern equivalent. These are considered revenue expenses and can be deducted from your rental income in the year they occur.
- An improvement is work that enhances or upgrades the property beyond its original state, such as adding an extension or installing a brand-new, high-spec kitchen where a basic one was before. These are capital expenses and cannot be claimed against your rental income. Instead, they are deducted from your Capital Gains Tax bill when you sell.
It is possible to time your maintenance strategically to lower your taxable income.
For example, if you’ve had a particularly profitable year and are nearing a higher tax threshold, bringing forward some planned repairs can reduce your taxable income for that year.
Replacing a worn-out carpet like-for-like or giving the property a full repaint are excellent ways to invest in your asset while simultaneously managing your tax liability.
5. Leverage Your Personal Allowances (and Your Partner's)
Lastly, do not overlook the allowances available to you as an individual. The Property Income Allowance lets you earn up to £1,000 of rental income tax-free each year, though if you claim it you cannot also claim your allowable expenses — so it is only worth using where your expenses come to less than £1,000.
And if your spouse or civil partner is in a lower tax bracket and you own properties jointly, you can even alter the split of beneficial ownership by using a Declaration of Trust, reducing the amount of tax you need to pay. Be aware that by default, HMRC assumes you own half each.
Making Tax Work For You
Ultimately, being a tax-savvy landlord isn't about finding shady landlord loopholes. Tax will always go more smoothly for you if you’re organised, proactive, and if you stay informed.
Keeping detailed digital records of every allowable rental property expense is the first step and most important step to achieving this.
Making Tax Digital for Income Tax started on 6 April 2026 for landlords with qualifying income over £50,000. It extends to those over £30,000 from April 2027, and over £20,000 from April 2028.
If you want to stay ahead, maximise your deductions, and make tax time less stressful, you will likely find Landlord Studio helpful.
Designed specifically for landlords, it makes tracking income and expenses effortless, helps you stay compliant, and gives you the financial clarity you need to make good decisions.
Create your free Landlord Studio account today and see how much simpler managing your portfolio can be.