


6 Tips for More Accurate Rental Accounting
As a landlord and property investor it’s your responsibility to ensure you keep accurate rental accounts compliant with HMRC regulations.


Read summarised version with:

ChatGPT

Gemini

Claude

Grok

Add as preferred on Google
Unless you’re a professional accountant or experienced financial pro, managing the accounts for your buy-to-let properties can feel overwhelming. It’s easy to miss expenses, misreport income, or lose key records, mistakes that are both time-consuming and stressful to fix.
However, as a landlord and property investor, it’s your legal responsibility to keep accurate financial records for HMRC and remain compliant with tax laws. More than that, if you want to grow your portfolio and use property as a long-term investment vehicle, understanding your numbers is non-negotiable.
Why You Need to Get Your Rental Accounting in Order Now
Since April 2026, landlords earning over £50,000 from property have had to digitally maintain and submit quarterly financial records as part of Making Tax Digital for Income Tax (MTD for IT). Those earning over £30,000 must comply from April 2027, and those over £20,000 from April 2028. Digital record keeping is no longer optional—it is a legal requirement.
If your own start date has not arrived yet, now is the time to implement digital accounting practices and get comfortable with MTD-ready software, such as Landlord Studio, which is recognised by HMRC. Adopting a robust system today will not only help you meet your obligations but also unlock powerful insights into your portfolio's financial performance.
In this article, we explore six essential tips to help you streamline your rental accounting and stay on top of your digital record keeping.
Rental Accounting Tips for Landlords
1. Separate Your Finances
The very first step to operating a successful rental is to ensure that you have that you are set up professionally. You should not be commingling your personal funds with your rental income funds.
Landlords and investors need to set up a separate bank account for their business-related operating expenses and income. When it comes tax time, this will make things far more simple. Instead of having to scroll through thousands of small potentially unrelated personal transactions you can instead look at your business account and know with some confidence that all of the transactions are related to your business in some way or another.
MTD requires quarterly submissions based on digital records, so having a clean, business-only transaction history will make compliance much easier.
2. Track Expenses in Real-Time
One of the most common mistakes landlords make is putting off their bookkeeping until the end of the year. This leads to missed deductions, lost receipts, and frustrating catch-up work.
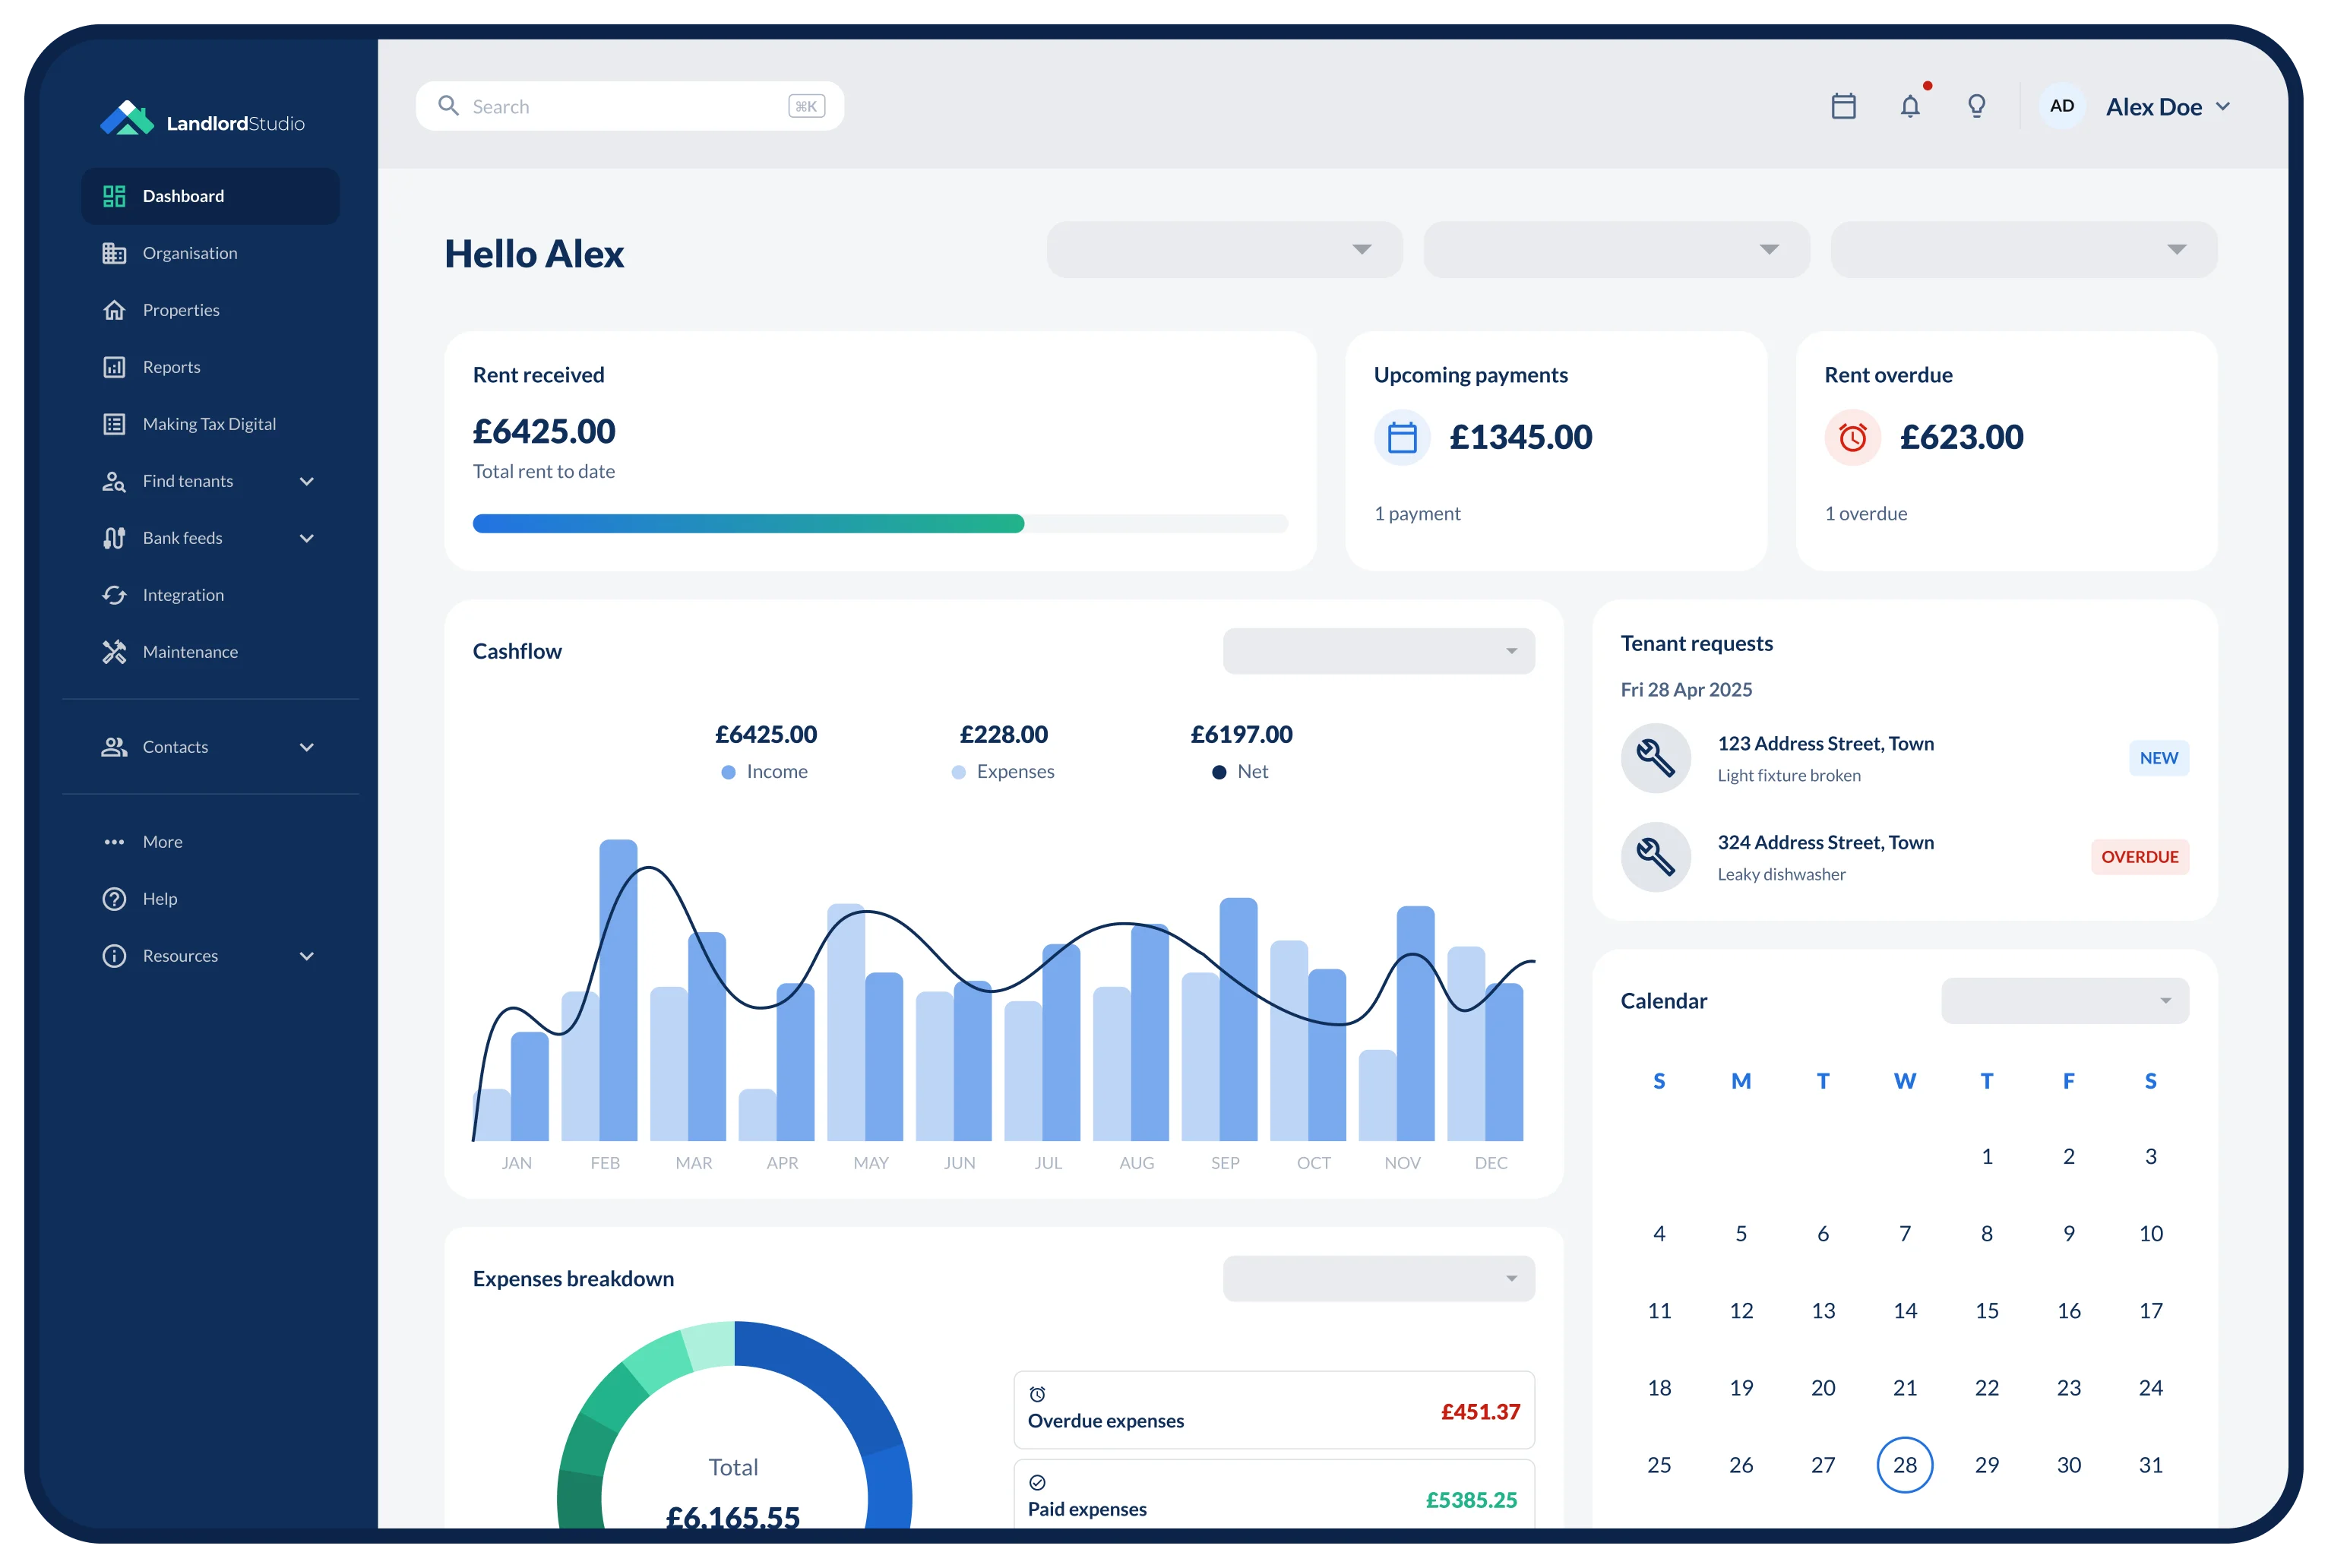
Instead, track your income and expenses in real-time. With Landlord Studio, for example, you can log expenses as they happen, digitise receipts on your phone, and instantly assign them to a property.
Real-time tracking ensures MTD-compliant digital records and helps you avoid HMRC penalties due to incomplete submissions. You can learn more about MTD here.

3. Store Supporting Documents With Your Rental Accounts
HMRC requires landlords to keep records—including receipts and invoices—for at least 5 years. Storing these as paper documents creates problems: they fade, they get lost, and they’re hard to organise.
Use a system that allows you to store documents securely in the cloud. With Landlord Studio, you can digitise receipts with the smart receipt scanner and upload and organise important documents—from utility bills to gas safety certificates to tenancy agreements—by property. These are securely backed up and instantly searchable from any device.
This digital approach isn’t just convenient—it’s essential for MTD.
4. Reconcile Your Rental Accounts With Your Bank Transactions
Open Banking is now the norm, and most modern accounting tools use it to auto-import your transactions.
These solutions have made it easy for businesses to access their transactions using software like Landlord Studio. Instead of printing off pages of bank statements and entering transaction details manually, simply go into the Landlord Studio app, open bank feeds, and click on the expense you want to reconcile. This is both more efficient and also removes the potential for human error.
At the end of the year, simply run your reports, share them with your accountant, and fill out your self-assessment.
5. Calculate Your Taxable Income and Allowable Expenses
To avoid surprise tax bills, you need to monitor your taxable income and allowable expenses throughout the year. Your rental accounting system should break these down on a monthly and quarterly basis so that you can understand your net income, plan ahead, and submit accurate information to HMRC.
Landlord Studio gives you instant access to key reports, such as Profit & Loss and Income & Expense statements, helping you stay tax-ready year-round.
Its also worth mentioning that, as part of Landlord Studio's MTD dashboard, you'll be get income tax forecasts based on real data, so there are no more end-of-year tax surprises.
6. Use the Right Rental Accounting Software
Trying to manage all this manually—especially now MTD is in force—is no longer realistic. The right software will help you track income and expenses, store receipts, reconcile transactions, calculate taxes, and generate reports—all in one place.
Landlord Studio is designed specifically for landlords. It’s an HMRC-recognised MTD solution that helps you stay compliant while saving time and stress. As your portfolio grows, tools like this become essential for scaling efficiently and making informed decisions.
Final Words: Prepare for MTD and Take Control of Your Rental Property Accounting
The tips in this article will not only save you time and improve the accuracy of your rental accounting and tax reporting, they’ll also ensure you meet the Making Tax Digital requirements.
Since April 2026, digital accounting has been mandatory for many landlords, and the remaining thresholds follow in 2027 and 2028. Rather than scrambling to adapt when your start date arrives, start now. Get your systems in place, digitise your records, and start using MTD-ready tools like Landlord Studio today.
While these tips will help most landlords, everyone’s financial situation is different. Speak with a qualified accountant for tailored advice and ensure your setup supports both your tax obligations and your long-term investment goals.
About Landlord Studio

Landlord Studio is an easy to use MTD compliant property management and accounting software designed for UK landlords.
Track income and expenses, run reports,, find and prescreen tenants, manage property maintenance, and more.
Stay Updated on Property Insights

Get weekly tips, tax updates, and landlord strategies straight to your inbox.
How to Submit your Second Quarterly MTD Submission
Missed your first MTD submission or unsure what changed? Learn how to file your second quarterly update correctly before the 7th November HMRC deadline.
Details:
Free
Hosted by:
Logan Ransley
When:
October 15, 2026
12:00pm BST
Duration:
45 minutes
Guest:
Logan Ransley, co-founder of Landlord Studio